Your Business Speaks in Numbers SERIES 1 The Nature of Finance

Practical finance for entrepreneurs who want to understand, make decisions, and grow through our series of…

«Your Business Speaks in Numbers»

Series 1 «The Nature of Finance»

What if one of the biggest risks in business isn’t low sales—but making decisions without understanding what the numbers are telling you?

When we start a business, we tend to focus on customers, products, sales, marketing, technology, and growth.

We rarely stop to ask a more fundamental question:

Can we actually afford it?

Business finance should not be a subject reserved for accountants, economists, or financial specialists.

Finance is a management tool.

And every entrepreneur, business owner, and manager can learn to use it.

You don’t need to become an accountant to understand your company’s finances.

You need to learn how to ask better questions, interpret information, and connect the numbers with the decisions you make every day.

Finance isn’t just about numbers.

Finance tells the economic story of a business.

And learning how to read that story can completely change the way you lead your company.

Finance Is the Language That Connects Decisions With Reality

Imagine owning a company whose sales are higher than they were last year.

Your team is excited.

Customers are coming in.

Revenue is growing.

But every month, you struggle to pay suppliers, payroll, or taxes.

How can a company sell more and still struggle to pay its bills?

One of the answers is understanding that sales, profit, and cash are not the same thing.

This is one of the first lessons every entrepreneur should learn.

Finance helps answer questions such as:

  • Are we profitable?
  • Do we have enough cash?
  • How much does it cost to operate?
  • Are we growing in a healthy way?
  • How much debt are we carrying?
  • How much capital do we need?
  • Which investments actually create value?
  • Can we afford to finance our growth?
  • What happens if sales decline?

Numbers don’t make decisions for us.

They help us make better decisions.

That is why financial thinking should be part of everyday business conversations—not something that only happens at the end of the month.

An entrepreneur who understands finance can communicate more effectively with accountants, bankers, investors, partners, and employees.

More importantly, they can understand their own business better.

What Does a Financial Executive Really Do?

For many years, people viewed the financial executive as the person responsible for reviewing numbers, preparing budgets, and controlling expenses.

Those responsibilities still matter.

But the modern finance function goes much further.

One of its most important responsibilities is helping the organization answer a fundamental question:

How should we use our limited resources to create value?

That involves three major decisions.

1. Where should we invest?

A company constantly has choices.

Should we invest in technology?

Equipment?

Advertising?

Training?

Inventory?

A new product?

A new location?

Not every investment is automatically a good investment.

The question isn’t simply:

“Can we afford it?”

The more important question is:

“Will this investment contribute to the future of the business?”

2. How should we finance those decisions?

Growth requires resources.

A company may use its own capital, reinvest profits, borrow money, bring in investors, or use other financing alternatives.

Every choice has consequences.

Debt can accelerate growth, but it also creates obligations.

A new investor can bring capital and expertise, but it also means sharing ownership and decision-making.

The finance function helps management evaluate those alternatives.

3. How should we manage our resources?

Even a profitable company can experience difficulties if its cash is poorly managed.

Finance also involves liquidity, working capital, risk management, financial planning, and responsible use of resources.

That’s why the financial executive should not be viewed simply as “the person who handles the numbers.”

The financial executive should be a strategic partner to leadership.

Financial Education Is Also Personal Development

Learning business finance doesn’t just improve the company.

It can transform the entrepreneur.

Why?

Because working with financial information develops important personal qualities:

discipline, patience, critical thinking, accountability, and decision-making.

Numbers can be uncomfortable because they often reveal reality without the emotional filter.

We may love a particular product, but the numbers may show that its margins are too low.

We may believe an investment will be spectacular, but the analysis may show that it will take too long to recover the capital.

We may feel that the company is growing rapidly, while the numbers reveal that debt is growing even faster.

Accepting that information requires maturity.

Financial intelligence means replacing:

“I think this will work.”

with:

“What evidence do we have that this will work?”

That doesn’t mean eliminating intuition.

It means combining:

intuition + information + experience + analysis.

A financially intelligent entrepreneur isn’t someone who never makes mistakes.

It is someone who learns to identify mistakes early enough to correct them—and has the courage to change direction when necessary.

Finance, Success, and Happiness: Growing Without Losing Your Purpose

There is a common misconception that business success is simply about making more money.

Money matters.

A business must be economically sustainable if it wants to survive, grow, employ people, and create value over time.

But profitability should not be the only definition of success.

A business can also create:

  • jobs;
  • useful products;
  • innovation;
  • opportunities;
  • employee well-being;
  • customer value;
  • positive community impact.

Finance should therefore serve a broader vision.

A good financial decision isn’t always the one that generates the highest immediate return.

Sometimes the best decision is investing in employee development.

Sometimes it’s strengthening a relationship with an important customer.

Sometimes it’s maintaining liquidity instead of expanding too quickly.

And sometimes the wisest decision is saying “no” to an attractive opportunity that doesn’t fit the company’s strategy.

Financial intelligence means understanding that every dollar represents a choice.

And behind every choice is a priority.

Managing finances therefore also means asking:

What kind of company do we want to build?

And perhaps even more importantly:

What kind of entrepreneur do we want to become?

Numbers Aren’t the Destination—They’re the Map

Learning finance doesn’t take away the passion of entrepreneurship.

It gives that passion a structure capable of supporting it.

Financial knowledge can help transform dreams into viable projects, projects into businesses, and businesses into organizations capable of creating long-term value.

You don’t have to know everything.

You simply have to begin.

Learn to read your key indicators.

Understand revenue and expenses.

Monitor cash.

Know your obligations.

Learn how much growth costs.

Understand how to evaluate an investment.

And most importantly, don’t be afraid of numbers.

Numbers aren’t there to judge you. They’re there to help you see.

🌟 Think…

An entrepreneur doesn’t need to predict the future perfectly. An entrepreneur needs to learn how to make better decisions with the information available today.

Your business can grow as you grow.

And one of the smartest investments you can make in your company is developing the ability to understand how it works financially.

Learning finance isn’t about learning how to count money. It’s about learning where to put your money so you can build the future you want.
References

Brigham, E. F., & Ehrhardt, M. C. (2022). Financial management: Theory & practice (16th ed.). Cengage.

International Accounting Standards Board. (2018). Conceptual framework for financial reporting. IFRS Foundation.

Ross, S. A., Westerfield, R. W., Jaffe, J., & Jordan, B. D. (2022). Corporate finance (13th ed.). McGraw-Hill.

Atrill, P. (2020). Financial management for decision makers (9th ed.). Pearson.

Gitman, L. J., Zutter, C. J., & Smart, S. B. (2021). Principles of managerial finance (15th ed.). Pearson.

Your Business Speaks in Numbers Series 1 The nature of finance

Practical finance for entrepreneurs who want to understand, make decisions, and grow through our series of…

«Your Business Speaks in Numbers»

Series 1 «The Nature of Finance»

Contenido aqui

References

Bibliografia Aqui

Titulo de Video

Titulo de Video

What Financial Statements Reveal to Non-Financial Executives in the U.S. Context

This article is part of the course
«Financial Statements for Non-Financial Directors»
Topic 2 Part 2

Introduction

Imagine leading a company in the United States—making decisions about hiring, investments, and strategy—while facing a set of financial reports that look more like a foreign language than a management tool. For many executives without a financial background, financial statements can feel intimidating. Yet, these documents are not just for accountants; they are essential instruments that help leaders understand the health of their organizations and make informed decisions.

This article, designed for a finance course for non-financial directors, explains in clear and practical terms what financial statements reveal, how they are structured, and why they matter. We will focus on the Balance Sheet, the Income Statement, the systems of recording and inventory valuation, and especially the Trial Balance and ledger accounts, which form the backbone of reliable reporting.


📊 Balance Sheet (Statement of Financial Position)

The Balance Sheet provides a snapshot of the company’s financial position at a specific point in time. It is divided into three main sections:

  • Assets: Resources the company owns or controls that are expected to bring future benefits.

    • Current assets: cash, accounts receivable, inventories.

    • Non-current assets: property, equipment, long-term investments.

  • Liabilities: Obligations the company owes to outsiders.

    • Current liabilities: accounts payable, short-term loans.

    • Long-term liabilities: bonds payable, long-term debt.

  • Equity: The residual interest of the owners. It includes contributed capital, retained earnings, and reserves.

Presentation formats

In the U.S., companies often present the Balance Sheet in report form (assets listed first, followed by liabilities and equity). Regardless of format, the fundamental equation must always hold:

Assets=Liabilities+Equity

This equation ensures that every resource is financed either by debt or by owners’ investment.


📑 Income Statement (Statement of Earnings)

The Income Statement tells the story of performance over a period.

  • Revenues: Primarily sales of goods or services, but may also include other income streams such as royalties or interest.

  • Costs:

    • In manufacturing: raw materials, direct labor, and overhead.

    • In retail/commerce: purchase cost of goods sold.

  • Expenses: Necessary outflows to operate the business.

    • Selling expenses: advertising, commissions.

    • Administrative expenses: office salaries, utilities.

    • Financial expenses: interest on loans.

The bottom line—net income or net loss—shows whether the company created value during the period.


⚙️ Recording Systems and Inventory Valuation

Accounting in the U.S. relies on structured systems:

  • Double-entry bookkeeping: Every transaction affects at least two accounts, ensuring balance.

  • Inventory valuation methods:

    • FIFO (First In, First Out).

    • LIFO (Last In, First Out)—allowed under U.S. GAAP but not under IFRS.

    • Weighted Average.

The chosen method directly impacts the Cost of Goods Sold (COGS) and therefore reported profits and taxes. For example, in times of rising prices, LIFO results in higher COGS and lower taxable income, while FIFO shows higher profits but higher taxes.


📏 Trial Balance and Ledger Accounts

This is where clarity emerges for non-financial leaders.

Trial Balance

The Trial Balance is a list of all accounts and their balances at a given time. Its purpose is to verify that total debits equal total credits, confirming the integrity of the double-entry system.

It acts as a checkpoint before preparing financial statements. If the trial balance does not balance, errors must be corrected before moving forward. For executives, this means confidence that the numbers presented in the Balance Sheet and Income Statement are reliable.

Ledger Accounts

The ledger accounts are the detailed records where transactions are classified: cash, accounts receivable, inventory, accounts payable, equity, etc. Each account provides insight into specific aspects of the business.

Their importance lies in:

  • Organizing financial information systematically.

  • Serving as the foundation for financial statements.

  • Allowing detailed analysis of each category (e.g., how much is owed to suppliers or how much inventory is on hand).

Together, the trial balance and ledger accounts form the skeleton of accounting. Without them, financial statements would lack accuracy and credibility.


🌟 Conclusion

Financial statements are not just technical documents; they are narratives that reveal the economic reality of a company. For non-financial executives in the United States, learning to interpret them is like mastering a new language—one that opens doors to trust, leadership, and strategic success.

The Balance Sheet, the Income Statement, the systems of recording, inventory valuation, the Trial Balance, and the ledger accounts are not isolated concepts. They are interconnected pieces that, when understood, empower leaders to make decisions with clarity and confidence.

References

  • Financial Accounting Standards Board (FASB). (2024). Accounting Standards Codification. Norwalk, CT: FASB.

  • Gibson, C. H. (2023). Financial Reporting and Analysis. Cengage Learning.

  • Horngren, C. T., Sundem, G. L., & Elliott, J. A. (2022). Introduction to Financial Accounting. Pearson.

  • Kieso, D. E., Weygandt, J. J., & Warfield, T. D. (2023). Intermediate Accounting. Wiley.

  • U.S. Securities and Exchange Commission (SEC). (2025). Guide to Financial Statements. Washington, D.C.: SEC.

What the balance sheet can—and can't—tell you about your company Part 2

The Art of Managing Your Business with Clear and Simple Accounting

Introduction

Running a business is not just about selling products or services; it is about building trust, making smart decisions, and ensuring long-term sustainability. Yet, many executives and entrepreneurs feel that accounting is a complex language filled with technical jargon and intimidating numbers. The truth is that, with clear foundations and a simple approach, accounting can become a powerful tool for growth and leadership.

This article explores the correct management of a business through a practical understanding of the main financial statements (Balance Sheet, Income Statement, Cash Flow Statement, and Statement of Changes in Equity), as well as the importance of recording systems, inventory valuation, and the trial balance. The ultimate goal is to help leaders interpret financial information and use it as a basis for strategic decision-making.


📊 The Foundations of Accounting

Accounting is the language of business. Its foundations rest on three pillars:

  • Orderly recording: every transaction must be documented.

  • Clear classification: separating revenues, expenses, assets, and liabilities.

  • Useful interpretation: numbers must be transformed into meaningful insights for decision-making.

Accounting is not an end in itself but a means to understand the financial health of the company.


📑 The Main Financial Statements

  • Balance Sheet: A snapshot of the company’s financial position at a specific moment. It shows assets (what the company owns), liabilities (what it owes), and equity (the owners’ stake). It answers: Are we financially solid?

  • Income Statement: A narrative of performance over a period. It reveals revenues, costs, and expenses, ultimately showing profit or loss. It answers: Are we profitable?

  • Cash Flow Statement: Often considered the most practical tool, it details the inflows and outflows of cash. It highlights liquidity and the company’s ability to meet obligations. It answers: Do we have enough cash to operate and grow?

  • Statement of Changes in Equity: This report explains how owners’ equity evolves over time. It reflects retained earnings, dividends, and contributions. It answers: How is the company’s value changing for its shareholders?

Together, these statements provide a comprehensive view of financial reality, allowing leaders to see both the static position and the dynamic movement of resources.


⚙️ Recording Systems and Inventory Valuation

The backbone of accounting lies in its recording systems:

  • Double-entry bookkeeping: Every transaction affects at least two accounts, ensuring balance and accuracy.

  • Inventory valuation methods: FIFO (First In, First Out), LIFO (Last In, First Out), and Weighted Average are common approaches. The chosen method directly impacts reported profits and taxes.

Accurate inventory valuation prevents hidden losses and ensures that profitability is measured correctly.


📏 The Trial Balance

The trial balance is a list of all accounts and their balances at a given time. Its purpose is to verify that debits equal credits, ensuring the integrity of the double-entry system. It is the checkpoint before preparing financial statements, detecting errors early and maintaining trust in the records.


🌟 Conclusion

Managing a business correctly requires discipline and clarity in accounting. Financial statements, recording systems, inventory valuation, and the trial balance are not just technical tools; they are strategic allies.

Beyond numbers, accounting is a language of trust and leadership. Learning to interpret it empowers executives and entrepreneurs to make decisions with confidence, ensuring both business success and personal peace of mind.

References

  • CINIF. (2024). Conceptual Framework of Financial Reporting Standards. Mexico: Consejo Mexicano de Normas de Información Financiera.

  • García, J. (2023). Basic Accounting for Entrepreneurs. Trillas Publishing.

  • Hernández, M. (2022). Financial Statement Interpretation. McGraw-Hill.

  • OACampus UAdeC. (2024). NIF A-2 Basic Principles Series. Universidad Autónoma de Coahuila.

  • vLex Mexico. (2025). Accounting and Recording Systems. vLex.

What the balance sheet can—and can't—tell you about your company Part 1

Understanding Financial Risk: Protecting Your Future While Building Your Dreams

Why Risk Matters More Than We Often Realize

Imagine spending years working hard, saving money, and making sacrifices to build a better future for yourself and your family. You finally decide to invest, hoping your money will grow and help you achieve important goals such as retirement, education, a home, or financial independence. Then, unexpectedly, markets fluctuate, inflation rises, currencies lose value, or an investment performs below expectations.

Experiences like these remind us that investing is not only about seeking returns; it is also about understanding and managing risk. Financial risk is a natural part of every investment decision. The good news is that risk does not have to be feared. When understood properly, it becomes a tool that helps us make better decisions and build a stronger financial future.

In a previous discussion, we explored the financial and securities system and how it connects investors with opportunities. Now, it is time to focus on one of the most important elements of investing: financial risk and how to align investment decisions with your personal goals, values, and tolerance for uncertainty.

Understanding Market and Credit Risk

Financial risk comes in many forms, but two of the most common are market risk and credit risk.

Market risk refers to the possibility that the value of an investment may fluctuate due to changes in economic conditions, interest rates, inflation, political events, consumer confidence, or global developments. Stocks, bonds, investment funds, and even real estate can be affected by market movements.

For example, an investor may purchase shares of a company expecting growth. However, economic uncertainty or changes in industry conditions may temporarily reduce the value of those shares. This does not necessarily mean the investment was a mistake; rather, it reflects the reality that markets move over time.

Credit risk, on the other hand, relates to the possibility that a borrower may fail to meet their financial obligations. When investing in bonds, debt instruments, or lending arrangements, investors rely on the ability of governments, companies, or individuals to repay what they owe. The lower the borrower’s ability to pay, the greater the credit risk.

Understanding these risks helps investors avoid making decisions based solely on emotions or short-term market events.

The Hidden Factors That Influence Investment Success

Many people focus exclusively on potential returns, but successful investing requires considering several interconnected factors.

Purchasing Power and Inflation

One of the greatest long-term financial risks is not always losing money—it can be losing purchasing power.

Inflation gradually increases the cost of goods and services. If your investments grow at a rate lower than inflation, your money may buy less in the future even if your account balance appears larger.

For this reason, investors should evaluate whether their investments have the potential to preserve or increase real purchasing power over time.

Profitability and Risk

There is a fundamental relationship between risk and return. Generally, investments that offer higher potential returns also involve higher levels of uncertainty.

This does not mean investors should always seek the highest returns available. Instead, they should seek an appropriate balance between potential growth and their ability to tolerate fluctuations.

The most suitable investment is not necessarily the one with the highest expected return, but the one that aligns with an individual’s goals and comfort level.

Profitability and Liquidity

Liquidity refers to how quickly an investment can be converted into cash without significantly affecting its value.

Some investments may offer attractive returns but require investors to commit funds for extended periods. Others provide easier access to money but may generate lower returns.

Finding the right balance between profitability and liquidity is essential, particularly when planning for emergencies, short-term objectives, or unexpected opportunities.

Devaluation and Currency Risk

In a global economy, currency movements can affect the value of investments and savings.

When a currency loses value relative to others, imported goods become more expensive, and purchasing power may decline. Investors should understand how currency fluctuations may influence their financial plans, especially when investing internationally or holding assets linked to foreign markets.

Opportunity Cost

Every financial decision involves a trade-off.

Opportunity cost represents the benefits that could have been gained from choosing an alternative option. For example, keeping all savings in a low-yield account may feel safe, but it may also limit long-term growth opportunities.

Evaluating opportunity costs helps investors think strategically rather than reactively.

Knowing Yourself: The Key to Risk Tolerance

Perhaps the most overlooked aspect of investing is self-awareness.

Risk tolerance refers to an individual’s ability and willingness to accept fluctuations in investment value. Some people remain calm during market volatility, while others experience significant stress when investments decline.

Neither approach is right or wrong. The important thing is to understand your personal comfort level and invest accordingly.

Factors that influence risk tolerance include:

  • Age and investment horizon.
  • Financial responsibilities.
  • Income stability.
  • Personal goals.
  • Previous investment experience.
  • Emotional response to uncertainty.

Investing beyond your comfort zone can lead to emotional decisions that undermine long-term success. Conversely, avoiding all risk may prevent your money from growing enough to meet future needs.

A thoughtful investment strategy recognizes both financial realities and human emotions.

Personal Growth, Financial Success, and Lasting Well-Being

Financial education is ultimately a form of personal development.

Learning about risk helps individuals become more confident, disciplined, and intentional in their decision-making. It encourages patience, long-term thinking, and a greater understanding of how daily choices influence future outcomes.

True financial success is not measured solely by wealth accumulation. It also includes peace of mind, freedom to pursue meaningful goals, and the ability to support the people and causes that matter most.

The most successful investors are often not those who predict markets perfectly, but those who remain committed to a well-designed plan, continue learning, and adapt responsibly to changing circumstances.

Conclusion

Financial risk is not an obstacle to success—it is a reality that accompanies every meaningful opportunity. By understanding market risk, credit risk, inflation, purchasing power, liquidity, devaluation, diversification, and opportunity cost, individuals can make more informed decisions and build greater confidence in their financial journey.

The future will always contain uncertainty, but knowledge transforms uncertainty into preparation. Every step taken to improve financial understanding is an investment in yourself, your family, and your dreams. The goal is not to eliminate risk entirely, but to manage it wisely so that your money works alongside your aspirations and supports a life of purpose, growth, and fulfillment.

References

Bodie, Z., Kane, A., & Marcus, A. J. (2024). Investments (13th ed.). McGraw-Hill Education.

Madura, J. (2023). Financial markets and institutions (14th ed.). Cengage Learning.

Mishkin, F. S., & Eakins, S. G. (2024). Financial markets and institutions (10th ed.). Pearson.

Reilly, F. K., & Brown, K. C. (2021). Investment analysis and portfolio management (11th ed.). Cengage Learning.

Ross, S. A., Westerfield, R. W., Jordan, B. D., Lim, J., & Tan, R. (2022). Fundamentals of corporate finance (5th ed.). McGraw-Hill Education.

Financial Education: The Art of Smart Decisions

The Business Model Canvas: Turning Ideas into Real Businesses

Introducción

Muchas personas sueñan con emprender. Algunas buscan libertad financiera. Otras desean resolver problemas, crear algo útil o construir una vida con mayor independencia.

Pero entre la inspiración y la realidad suele aparecer una pregunta difícil:

¿Por dónde empiezo?

Esa duda es normal. Todo emprendedor la vive. Lo importante no es tener todas las respuestas, sino contar con una guía clara.

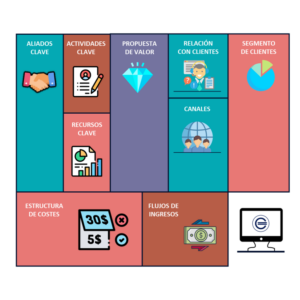
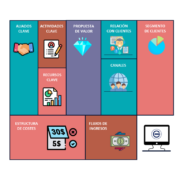
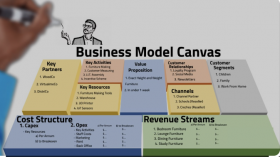
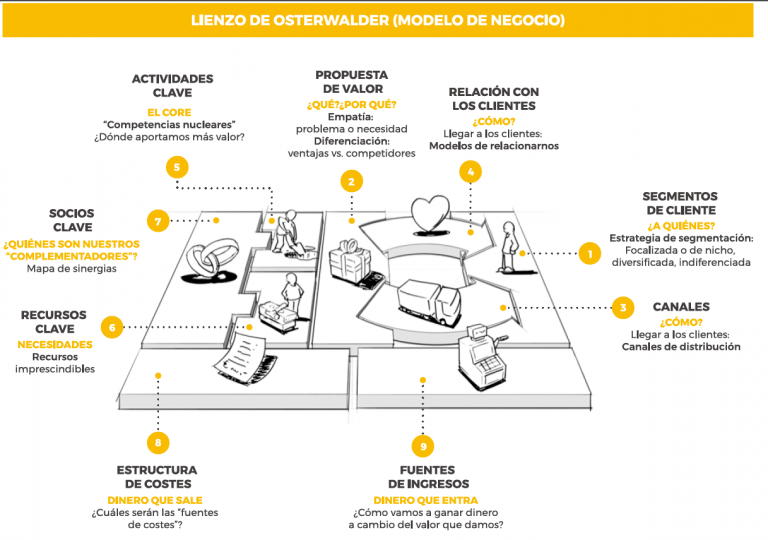
Una de las herramientas más útiles para lograrlo es el Business Model Canvas, que permite entender cómo un negocio crea valor, entrega valor y genera ingresos.


1. Empieza con el Cliente

Todo negocio comienza con personas.

Por eso el primer paso es identificar los segmentos de clientes que más se beneficiarán de tu propuesta.

Muchos emprendedores intentan venderle a todos. Sin embargo, suele ser mejor empezar con uno:

  • ¿Quién tiene el problema más urgente?
  • ¿Quién puede pagar hoy?
  • ¿Quién valorará más tu solución?

El enfoque genera avance.


2. Propuesta de Valor: Por Qué Te Eligen

La propuesta de valor explica por qué un cliente te escogería.

Puede ser:

  • Más rápido
  • Más fácil
  • Más económico
  • Más confiable
  • Más personalizado
  • Más innovador

Las personas no compran productos: compran resultados.


3. Canales y Relaciones

Los canales son la forma en que llegas al cliente:

  • Redes sociales
  • Tienda en línea
  • Punto físico
  • Referidos
  • Alianzas

Las relaciones con clientes crean confianza:

  • Atención personalizada
  • Automatización
  • Comunidad
  • Membresías
  • Seguimiento postventa

Conseguir clientes importa. Conservarlos importa más.


4. Ingresos, Recursos, Actividades y Alianzas

Los ingresos pueden ser:

  • Venta única
  • Suscripción
  • Membresía
  • Contratos recurrentes

Los recursos clave incluyen:

  • Herramientas
  • Marca
  • Equipo humano
  • Capital

Las actividades clave incluyen:

  • Marketing
  • Ventas
  • Producción
  • Servicio

Las alianzas estratégicas aceleran el crecimiento.

Innovar rara vez es un esfuerzo solitario.


Conclusión

El Business Model Canvas convierte la incertidumbre en claridad.

Cuando entiendes al cliente, defines valor y organizas recursos, una idea deja de ser sueño y empieza a ser negocio.

The Business Model Canvas: A Tool for Entrepreneurs and Innovators

¿Quieres iniciar tu propio negocio? ¿Eres emprendedor y deseas acelerar el crecimiento rentable mejorando tu modelo de negocio? ¿Eres intraemprendedor dentro de una organización con una nueva idea capaz de hacer sonreír a tus clientes y llorar a tus competidores? Si es así, el Business Model Canvas es el mejor lugar para comenzar.

Bibliografia aqui

Cap 6 Canvas - Telling your Story

How Will Customers Find You and Stay With You? Mastering Channels and Customer Relationships in the Business Model Canvas

Introduction

Many businesses fail not because their product is bad, but because customers never discover it—or they buy once and never return. This can be painful for entrepreneurs who invest time, money, and hope into something meaningful.

A great idea needs more than quality. It needs visibility, trust, and connection. That is why two of the most powerful parts of the Business Model Canvas are Channels and Customer Relationships.

These blocks help answer practical questions: How will people find us? How will we serve them? Why will they come back? They also push founders to observe the world around them: What regulations are coming? How is society changing? Who are our competitors, and what are they doing well?

When understood correctly, these blocks turn a business into a living relationship with the market.


## 1. Channels: How Your Value Reaches the Customer

Channels are the ways a company communicates with customers and delivers its value proposition. Even the best product can struggle if the wrong channel is used.

Common channels include:

  • Website or online store
  • Social media
  • Email marketing
  • Retail stores
  • Distributors
  • Mobile apps
  • Events and networking
  • Partnerships and affiliates

Good channels perform five tasks:

  1. Create awareness
  2. Help customers evaluate your offer
  3. Make purchasing easy
  4. Deliver the product or service
  5. Provide after-sales support

For example:

  • A handmade brand may grow through Instagram and marketplaces.
  • A consulting firm may rely on LinkedIn and referrals.
  • A food business may need delivery apps and local presence.

The goal is not to be everywhere. It is to be where your customers already are.


## 2. Customer Relationships: Why They Return and Recommend You

Customer relationships define how you interact with people before, during, and after the sale.

Types of relationships include:

  • Personal assistance
  • Self-service
  • Automated service
  • Communities
  • Membership programs
  • Dedicated account management
  • Co-creation (customers help improve products)

Strong relationships build loyalty, reduce marketing costs, and create trust.

Ask yourself:

  • How quickly do we respond?
  • Do customers feel heard?
  • Is buying simple and pleasant?
  • Do we stay connected after purchase?

A first sale creates income. A second sale creates stability.

In many industries, kindness and consistency are competitive advantages.


## 3. What Regulations Are Coming? How Is Society Changing?

Smart entrepreneurs do not only study customers—they study the future.

Regulations and social trends influence channels and relationships more each year. Depending on the country and industry, common changes include:

Emerging Regulations

  • Data privacy rules
  • Consumer transparency requirements
  • Digital invoicing and tax compliance
  • Sustainability reporting
  • Accessibility standards for websites and services

Social Changes

  • Customers expect faster responses
  • More people prefer online purchasing
  • Trust in reviews and communities is growing
  • Buyers value ethical and sustainable brands
  • Personalization is becoming normal

So when someone asks, “What regulations are coming? How is this society changing, Carl?” the real lesson is this:

Businesses must stay curious, adaptable, and informed.

Companies that listen early adjust faster.


## 4. Who Are Your Competitors? What Advantages Do They Have?

Competitors are not enemies—they are teachers.

Study three things:

Their Channels

Where do they attract attention? Social media? Stores? Partnerships?

Their Relationships

Do they offer faster service, stronger communities, subscriptions, loyalty rewards?

Their Business Model Advantages

  • Lower costs
  • Better convenience
  • Stronger brand recognition
  • Better technology
  • Better customer experience
  • Faster delivery
  • More trust

Then ask:

  • What do they do well?
  • Where are customers still frustrated?
  • How can we be different instead of copying?

Success often comes not from being bigger—but from being more relevant.


Conclusion

Channels and Customer Relationships remind us that businesses grow through connection, not only transactions.

Your product may be excellent—but if people cannot find you, trust you, or remember you, growth becomes difficult.

Ask yourself today:

Where will customers meet us? How will they feel when they do?

That answer can transform a startup into a brand people choose again and again.

Bibliography (APA)

Blank, S., & Dorf, B. (2020). The startup owner’s manual. K&S Ranch.
Osterwalder, A., & Pigneur, Y. (2010). Business model generation. Wiley.
Ries, E. (2011). The lean startup. Crown Business.
Kotler, P., & Keller, K. (2016). Marketing management (15th ed.). Pearson.

Cap 5 Canvas - Proving It

World Autism Awareness Day: Empathy, Planning, and the Power of Understanding

Seeing the World Through a Different Lens

Imagine navigating a world that feels louder, brighter, and more unpredictable than it does for others. For millions of individuals living with Autism Spectrum Disorder (ASD), this is part of everyday life.

Recognized every April 2nd as World Autism Awareness Day, this day is not just about awareness—it is about understanding, inclusion, and action. As a financial and life insurance advisor, I’ve seen firsthand how empathy combined with proper planning can transform uncertainty into stability and opportunity.


Health and Emotional Well-Being: The Foundation of Stability

Autism is not a limitation—it is a different way of experiencing the world. However, individuals on the spectrum may face challenges related to communication, sensory processing, or social interaction.

Families often benefit from early intervention, therapies, and consistent routines. Emotional well-being improves significantly when environments are supportive and predictable.

Empathy plays a central role here. Understanding that behaviors often communicate unmet needs allows families and communities to respond with patience instead of frustration.


Financial Planning: Building Security for the Long Term

One of the most overlooked aspects of autism support is financial planning. Caring for a loved one with ASD often involves long-term commitments, including healthcare, specialized education, and assisted living.

Tools such as life insurance, education funds, and structured savings plans can help families prepare for the future. A well-designed life insurance policy, for instance, can ensure that dependents are financially protected even in the absence of a primary caregiver.

The goal is not complexity—it is clarity. Simple, consistent financial habits can provide peace of mind and protect what matters most.


Self-Improvement and Inclusion: Growth for Everyone

Autism awareness is not only about those diagnosed—it is about all of us. It challenges society to become more inclusive, patient, and adaptable.

For individuals, learning about autism fosters emotional intelligence. For organizations, it opens doors to diverse talent, as many individuals with ASD bring unique strengths such as attention to detail, creativity, and analytical thinking.

Personal growth begins when we shift from judgment to curiosity.


Success and Happiness: Redefining What Matters

Success should not be measured by conformity but by well-being and fulfillment. Many individuals with autism lead meaningful, productive lives when given the right support systems.

Families who embrace both emotional and financial preparedness often report greater peace and resilience. Happiness, in this context, comes from acceptance, planning, and connection.


Awareness That Leads to Action

World Autism Awareness Day reminds us that understanding is the first step—but action is what creates change.

By combining empathy with practical tools like financial planning and protection strategies, we can build a more inclusive and secure future for everyone.

Because true awareness is not just about seeing differences—it’s about supporting them with intention.

Bibliography 

  • American Psychiatric Association. (2022). Diagnostic and statistical manual of mental disorders (5th ed., text rev.).
  • World Health Organization. (2023). Autism spectrum disorders.
  • United Nations. (2024). World Autism Awareness Day.
  • Autism Speaks. (2023). What is Autism?
  • National Institute of Mental Health. (2022). Autism Spectrum Disorder.

Encabezado de Video aqui

What Will Customers Happily Pay For? Mastering Revenue Streams and Key Resources in the Business Model Canvas

Introduction

Many people start a business with passion, talent, and a dream—but dreams alone do not pay suppliers, salaries, or rent. A strong business idea becomes sustainable when it clearly answers two essential questions: How will money come in? and What do we need to deliver value consistently?

This is where the Business Model Canvas becomes powerful. It helps entrepreneurs organize ideas into a practical model. In this article, we focus on two vital areas: Revenue Streams (how the business earns money) and Key Resources (what the business needs to operate and grow).

When these two pieces are clear, a business gains direction, confidence, and the ability to grow with purpose.


## 1. Revenue Streams: What Are Customers Willing to Pay For?

Revenue streams represent the money a company receives from each customer segment. But the real question is deeper:

What problem is valuable enough for customers to spend money solving?

Customers usually pay for one or more of these forms of value:

  • Convenience – saving time or effort
  • Quality – reliability, durability, excellence
  • Status – image, prestige, identity
  • Savings – lower cost over time
  • Security – trust, guarantees, peace of mind
  • Experience – enjoyment, comfort, emotion
  • Results – measurable transformation

For example:

  • A busy parent pays for meal delivery because it saves time.
  • A company pays premium software because it improves efficiency.
  • A student pays for coaching because it increases confidence and results.

The lesson is simple: customers do not buy products—they buy outcomes.


## 2. How to Determine Your Pricing Strategy

Pricing is emotional and strategic. Charging too little may create distrust or losses. Charging too much without value creates resistance.

Here are practical pricing techniques:

Cost-Plus Pricing

Calculate total costs and add a profit margin.

Best for: physical products, simple operations.

Value-Based Pricing

Price according to the value perceived by the customer.

Best for: consulting, premium brands, specialized services.

Competitor-Based Pricing

Compare similar market offers and position yourself lower, equal, or higher.

Best for: competitive industries.

Tiered Pricing

Offer multiple levels (Basic, Pro, Premium).

Best for: software, memberships, coaching.

Test and Learn

Launch with one price, collect feedback, and improve.

Best for: startups.

Questions to Ask Before Setting a Price

  • What problem am I solving?
  • How urgent is that problem?
  • What alternatives exist?
  • How much money or time do I save the customer?
  • What experience am I creating?

Good pricing respects both the customer and the business.


## 3. Key Resources: What Do You Need to Deliver Value?

Key resources are the assets required to create and deliver your value proposition.

These usually fall into four categories:

Physical Resources

Equipment, office, inventory, vehicles, tools, technology.

Intellectual Resources

Brand, know-how, systems, patents, content, customer data.

Human Resources

Founders, employees, freelancers, advisors, customer service.

Financial Resources

Cash flow, savings, investors, credit lines.

Example:

An online fitness coach may need:

  • Laptop and camera
  • Coaching methodology
  • Social media presence
  • Scheduling software
  • Energy, discipline, communication skills
  • Startup capital

The key is not owning everything. It is knowing what is essential.


## 4. Why This Matters for Success, Confidence, and Happiness

Many entrepreneurs feel stress because they are working hard without clarity. A business model reduces uncertainty.

When you understand:

  • who pays,
  • why they pay,
  • how much they pay,
  • and what you need to serve them,

you make better decisions and avoid wasting energy.

This also supports personal growth. You become more disciplined, strategic, and resilient. A business built with intention can create income—but also freedom, meaning, and pride.

Success is not only revenue. It is building something useful and sustainable.


Conclusion

The Business Model Canvas reminds us that a business is more than an idea—it is a system of value. Revenue streams show how trust becomes income. Key resources show what must be protected, developed, and strengthened.

If you are starting a business, ask yourself today:

What value will people gladly pay for—and what do I truly need to deliver it well?

The clearer your answer, the stronger your future becomes.

Bibliography (APA)

Blank, S., & Dorf, B. (2020). The startup owner’s manual. K&S Ranch.
Osterwalder, A., & Pigneur, Y. (2010). Business model generation. Wiley.
Ries, E. (2011). The lean startup. Crown Business.
Kotler, P., & Keller, K. (2016). Marketing management (15th ed.). Pearson.

Cap 4 Canvas - Navegando en tu entorno

14 Essential Keys for Building a Strong and Sustainable Financial Plan

Creating a solid financial plan isn’t just about saving money—it’s about developing habits, systems, and protections that allow you to grow, adapt, and stay secure no matter what life brings. Below are fourteen essential keys that anyone can apply, whether you’re just starting your financial journey or refining an existing plan.


1. Compare Prices Before You Buy

The internet has made price comparison effortless. Taking a few minutes to check multiple stores can save you 10–20% on regular purchases. Over time, these small savings compound into meaningful financial breathing room.


2. Pay in Cash When Discounts Are Offered

If a store offers a discount for paying upfront, take it. Paying less today is always better than paying more over time. You also avoid long-term commitments and interest charges.


3. Avoid Using Credit Cards When You Have Debt

Credit cards are powerful tools, but they can become traps when used without discipline. If you’re already in debt, pause credit card use until you regain control. This helps you see your real spending patterns and prioritize what truly matters.


4. Apply the 50–30–20 Rule

This simple framework keeps your finances balanced:

  • 50% for essential expenses

  • 30% for lifestyle and leisure

  • 20% for debt repayment or savings/investments

It’s a structure that promotes stability and long-term growth.


5. Set Realistic Financial Goals

Overestimating returns or underestimating risks leads to frustration. If you expect a 10% annual return, plan for 8–9% instead. This buffer protects you from market fluctuations and unexpected events.


6. Educate Yourself Continuously

Financial literacy is one of the most valuable assets you can build. The more you learn about investing, budgeting, and economic trends, the better your decisions will be.


7. Build an Emergency Fund

Life is unpredictable. A dedicated emergency fund protects you from falling into debt when unexpected expenses arise—car repairs, medical bills, or job loss.


8. Use Credit Cards Only When They Benefit You

Credit cards can work in your favor when used strategically:

  • Interest‑free installments

  • Rewards, points, or travel miles

  • Purchase protections

Use them only when they add value—not when they create debt.


9. Live Within Your Means

Lifestyle inflation is one of the biggest threats to financial stability. Avoid comparing yourself to others or making impulse purchases that exceed your income. Wealth grows through discipline, not appearances.


10. Buy Only What You Need

We all have spending weaknesses. Identify yours and create systems to control them—like sticking to a shopping list or waiting 24 hours before making non‑essential purchases.


11. Review Your Goals Monthly

Long‑term goals only work when broken into smaller checkpoints. Monthly reviews help you adjust, stay motivated, and track your progress.


12. Track Your Income and Expenses Regularly

You can’t manage what you don’t measure. Daily or weekly tracking gives you clarity and control, allowing you to make informed decisions instead of relying on guesswork.


13. Set Clear, Measurable, and Achievable Goals

Vague goals lead nowhere. Define specific targets—amounts, deadlines, and steps. This transforms your financial plan into a roadmap rather than a wish.


14. Include Insurance as a Core Part of Your Financial Plan

Insurance is often overlooked, yet it’s one of the most important pillars of financial stability. Proper coverage protects your wealth, your family, and your long‑term goals.

Key types of insurance to consider:

  • Health insurance: prevents medical emergencies from becoming financial catastrophes.

  • Life insurance: protects your family’s future.

  • Auto and home insurance: safeguard your assets.

  • Disability insurance: replaces income if you’re unable to work.

Insurance isn’t an expense—it’s a shield that preserves everything you’ve worked for.


Conclusion

Financial planning is not a one‑time task but a lifelong practice. These fourteen keys work together to create a system of clarity, protection, discipline, and growth. When you apply them consistently, you build not just wealth—but peace of mind.

References 

García, L. (2022). Fundamentos de educación financiera. Editorial Alfa. Ramsey, D. (2019). The Total Money Makeover. Thomas Nelson. Suze Orman. (2020). The Ultimate Retirement Guide for 50+. Hay House. OECD. (2023). Financial Literacy and Financial Education. https://www.oecd.org Investopedia. (2024). Personal Finance Basics. https://www.investopedia.com

The 13 Essential Keys to Smart Financial Planning

Creating Prototypes: The Business Model Canvas

Creating Prototypes: The Business Model Canvas
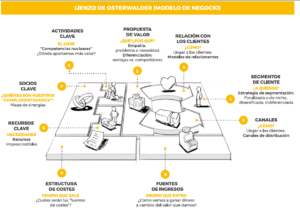
When creating a business model using the Business Model Canvas methodology, you can think of the business model as a story—a story of how your company will create, deliver, and capture value. And like any story, it might be one you’ve heard time and time again.

For example, you can start with what most people emphasize: the value proposition.

If it’s a trip for retirees, the next step is to decide who you can sell it to. It makes sense to define an ideal segment as baby boomers, since the Baby Boomer Generation (1946–1964) comprises people between 56 and 73 years old, characterized by being committed, self-sufficient, and competitive.

The next step is to outline how you will reach them, and yes, that could be through a website. Another point is to define how this will generate revenue, which would involve setting sales fees.

Another question to resolve is what key resources are needed to offer all of this and how we achieve a reliable website with brand recognition.

From this, it may emerge that the key activities will be marketing, the website, and its maintenance. And finally, the other big question is, where will the costs come from? What will sales, the development of the marketing platform, and all of this cost? By resolving all of the above, we could say that we have the first model. But this would only be a step forward.

Predictable models can work, but they rarely provide a competitive advantage. Therefore, one should not settle for a first idea. To compete in a world where the best model wins, one will have to think more and explore alternatives. For example, a prototype of a model where achieving the value proposition can be done at minimal cost or for free.

This will change everything instantly. This realistic model may not be found, but exploring it will force you to think hard about potential alternatives. As an entrepreneur, you must be thinking about the model in a 24/7 environment, that is, all the time. Now, you might think you already have a tool for structuring ideas into rapid prototypes to consider with your team, if needed.

By using this tool, and being optimistic, you could end up with a disruptive model that changes an entire industry, like Skype with its freemium model, or espresso, which became a multi-million dollar business by disrupting such a market and establishing itself as a coffee brewing technique.

In fact, understanding innovative, or simply successful, business models in other industries can be a great way to start achieving your own breakthrough. There’s no right or wrong way to do it, just three rules to get started.

First, focus on the business model. Not just your product, technology, or service.

Second, don’t fall in love with the first models. The best models are built on smart and unexpected elements, and that comes from creating many less obvious versions.

Which leads to the third rule. Interact by testing your models proactively and in a timely manner in the real world. How do you do that? That’s a topic for another time.

The important thing to consider is that if used correctly, Canvases can also serve as prototyping tools.

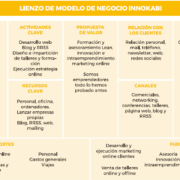
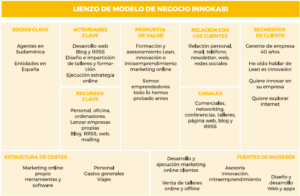
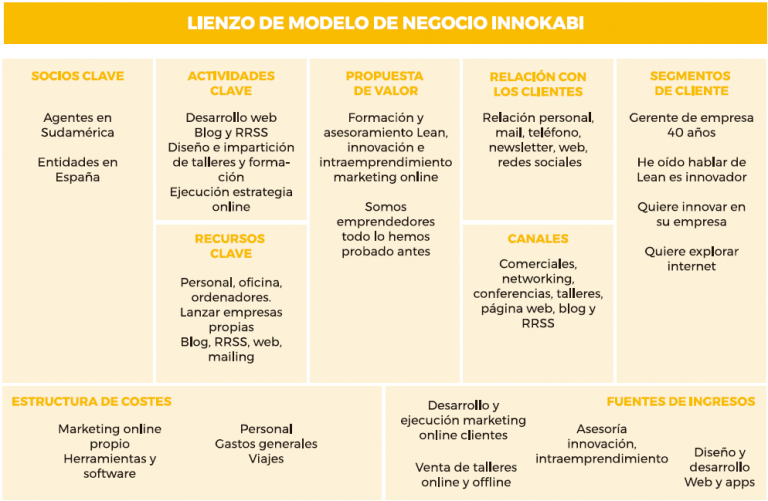
For inspiration, let’s look at the following example from Innokabi, where the canvas is used to develop the business model for their website:

Lean Canvas:

This canvas is based on Lean Startup methodologies. It’s an adaptation of Osterwalder’s model, but for entrepreneurs and innovators just starting out (not established companies). The right side represents the environment (market/society), while the left side represents the product/service.

This canvas uses a launch approach based on validation and scientific experimentation in an interactive way to shorten the processes of developing services/products, measuring progress, and obtaining feedback from target users. It’s best suited for developing services or entrepreneurial initiatives.

The following figure describes the different blocks of this canvas:

The use of these canvases as prototyping tools for innovation projects is valid and useful for the following reasons:


They serve as «templates» for working on projects collectively. They are very convenient tools for team reflection.

They are a very concise and powerful «visual narrative.» As you progress through them, they are excellent for explaining or communicating the critical aspects of the project.

They help you think in a structured way. They consist of «thinking boxes» that help the team not miss anything important.

They allow you to set the boundaries of the project (product or service) and mitigate the temptation to over-specify it by emphasizing the value perceived by users or beneficiary groups.

Remember that for a project to be viable, it needs proper management of its financial sustainability.
Crazy ideas like Airbnb, Uber, or Snapchat require more than incredible engineering knowledge. Therefore, prototyping crazy ideas can help us succeed, especially in a world where uncertainty reigns.

Bibliografia aqui

Cap 3 Canvas - Creacion de Prototipos