
Understanding Financial Risk: Protecting Your Future While Building Your Dreams
/0 Comentarios/en Finanzas/por JORGE MONTES DE OCAWhy Risk Matters More Than We Often Realize
Imagine spending years working hard, saving money, and making sacrifices to build a better future for yourself and your family. You finally decide to invest, hoping your money will grow and help you achieve important goals such as retirement, education, a home, or financial independence. Then, unexpectedly, markets fluctuate, inflation rises, currencies lose value, or an investment performs below expectations.
Experiences like these remind us that investing is not only about seeking returns; it is also about understanding and managing risk. Financial risk is a natural part of every investment decision. The good news is that risk does not have to be feared. When understood properly, it becomes a tool that helps us make better decisions and build a stronger financial future.
In a previous discussion, we explored the financial and securities system and how it connects investors with opportunities. Now, it is time to focus on one of the most important elements of investing: financial risk and how to align investment decisions with your personal goals, values, and tolerance for uncertainty.
Understanding Market and Credit Risk
Financial risk comes in many forms, but two of the most common are market risk and credit risk.
Market risk refers to the possibility that the value of an investment may fluctuate due to changes in economic conditions, interest rates, inflation, political events, consumer confidence, or global developments. Stocks, bonds, investment funds, and even real estate can be affected by market movements.
For example, an investor may purchase shares of a company expecting growth. However, economic uncertainty or changes in industry conditions may temporarily reduce the value of those shares. This does not necessarily mean the investment was a mistake; rather, it reflects the reality that markets move over time.
Credit risk, on the other hand, relates to the possibility that a borrower may fail to meet their financial obligations. When investing in bonds, debt instruments, or lending arrangements, investors rely on the ability of governments, companies, or individuals to repay what they owe. The lower the borrower’s ability to pay, the greater the credit risk.
Understanding these risks helps investors avoid making decisions based solely on emotions or short-term market events.
The Hidden Factors That Influence Investment Success
Many people focus exclusively on potential returns, but successful investing requires considering several interconnected factors.
Purchasing Power and Inflation
One of the greatest long-term financial risks is not always losing money—it can be losing purchasing power.
Inflation gradually increases the cost of goods and services. If your investments grow at a rate lower than inflation, your money may buy less in the future even if your account balance appears larger.
For this reason, investors should evaluate whether their investments have the potential to preserve or increase real purchasing power over time.
Profitability and Risk
There is a fundamental relationship between risk and return. Generally, investments that offer higher potential returns also involve higher levels of uncertainty.
This does not mean investors should always seek the highest returns available. Instead, they should seek an appropriate balance between potential growth and their ability to tolerate fluctuations.
The most suitable investment is not necessarily the one with the highest expected return, but the one that aligns with an individual’s goals and comfort level.
Profitability and Liquidity
Liquidity refers to how quickly an investment can be converted into cash without significantly affecting its value.
Some investments may offer attractive returns but require investors to commit funds for extended periods. Others provide easier access to money but may generate lower returns.
Finding the right balance between profitability and liquidity is essential, particularly when planning for emergencies, short-term objectives, or unexpected opportunities.
Devaluation and Currency Risk
In a global economy, currency movements can affect the value of investments and savings.
When a currency loses value relative to others, imported goods become more expensive, and purchasing power may decline. Investors should understand how currency fluctuations may influence their financial plans, especially when investing internationally or holding assets linked to foreign markets.
Opportunity Cost
Every financial decision involves a trade-off.
Opportunity cost represents the benefits that could have been gained from choosing an alternative option. For example, keeping all savings in a low-yield account may feel safe, but it may also limit long-term growth opportunities.
Evaluating opportunity costs helps investors think strategically rather than reactively.
Knowing Yourself: The Key to Risk Tolerance
Perhaps the most overlooked aspect of investing is self-awareness.
Risk tolerance refers to an individual’s ability and willingness to accept fluctuations in investment value. Some people remain calm during market volatility, while others experience significant stress when investments decline.
Neither approach is right or wrong. The important thing is to understand your personal comfort level and invest accordingly.
Factors that influence risk tolerance include:
- Age and investment horizon.
- Financial responsibilities.
- Income stability.
- Personal goals.
- Previous investment experience.
- Emotional response to uncertainty.
Investing beyond your comfort zone can lead to emotional decisions that undermine long-term success. Conversely, avoiding all risk may prevent your money from growing enough to meet future needs.
A thoughtful investment strategy recognizes both financial realities and human emotions.
Personal Growth, Financial Success, and Lasting Well-Being
Financial education is ultimately a form of personal development.
Learning about risk helps individuals become more confident, disciplined, and intentional in their decision-making. It encourages patience, long-term thinking, and a greater understanding of how daily choices influence future outcomes.
True financial success is not measured solely by wealth accumulation. It also includes peace of mind, freedom to pursue meaningful goals, and the ability to support the people and causes that matter most.
The most successful investors are often not those who predict markets perfectly, but those who remain committed to a well-designed plan, continue learning, and adapt responsibly to changing circumstances.
Conclusion
Financial risk is not an obstacle to success—it is a reality that accompanies every meaningful opportunity. By understanding market risk, credit risk, inflation, purchasing power, liquidity, devaluation, diversification, and opportunity cost, individuals can make more informed decisions and build greater confidence in their financial journey.
The future will always contain uncertainty, but knowledge transforms uncertainty into preparation. Every step taken to improve financial understanding is an investment in yourself, your family, and your dreams. The goal is not to eliminate risk entirely, but to manage it wisely so that your money works alongside your aspirations and supports a life of purpose, growth, and fulfillment.
References
Bodie, Z., Kane, A., & Marcus, A. J. (2024). Investments (13th ed.). McGraw-Hill Education.
Madura, J. (2023). Financial markets and institutions (14th ed.). Cengage Learning.
Mishkin, F. S., & Eakins, S. G. (2024). Financial markets and institutions (10th ed.). Pearson.
Reilly, F. K., & Brown, K. C. (2021). Investment analysis and portfolio management (11th ed.). Cengage Learning.
Ross, S. A., Westerfield, R. W., Jordan, B. D., Lim, J., & Tan, R. (2022). Fundamentals of corporate finance (5th ed.). McGraw-Hill Education.
Financial Education: The Art of Smart Decisions

Differences between Plan, Program, Project, Activity, and Task
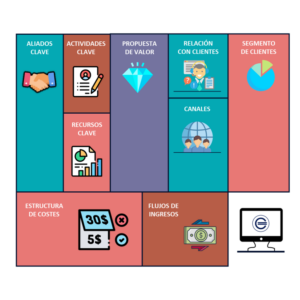
How Will Customers Find You and Stay With You? Mastering Channels and Customer Relationships in the Business Model Canvas

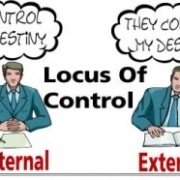

 We have already seen the difference between internal locus of control and external locus of control, and that this implies that I, as a person, attribute my success and failure to my own actions, to my own initiatives. This is called internal locus of control, while external locus of control implies that I, as a person, attribute the results I have in life to luck, to fate, to other external factors, and to my actions.