Listado de la etiqueta: Financial Situation

Entrepreneurial Mindset Ep 4 Failure Isn’t the End: How to Turn Mistakes Into Learning

This article is Episode 4 of our Series:

Entrepreneurial Mindset

Successful entrepreneurs don’t necessarily fail less. They learn, adapt, and move forward.


Introduction: The Story Nobody Wants to Tell

Imagine spending months building a business.

You invest your savings.

You sacrifice weekends.

You convince people to believe in your idea.

You finally launch.

And then…

Nothing happens.

Sales are disappointing.

Customers don’t respond.

The strategy doesn’t work.

The money starts running out.

And suddenly, one painful question enters your mind:

“Maybe I’m just not cut out for this.”

For many entrepreneurs, that moment feels like the end of the story.

But it doesn’t have to be.

There is an enormous difference between saying:

“I failed.”

and saying:

“This attempt didn’t work.”

The first statement turns an outcome into an identity.

The second turns an outcome into information.

And that distinction can completely change the way you approach entrepreneurship.

A failed launch doesn’t automatically mean you’re a bad entrepreneur.

A lost client doesn’t mean you’re a poor salesperson.

A failed investment doesn’t mean you have no business sense.

A business that closes doesn’t erase everything you learned while building it.

Failure is an outcome. Learning is a choice.


Failure as Information

Entrepreneurs love data.

Market research.

Customer surveys.

Financial projections.

Competitive analysis.

Sales forecasts.

All of these things are useful.

But there is one source of information that no spreadsheet can completely replace:

Real-world experience.

You can predict how customers might respond to a product.

But eventually, you have to put it in front of them.

And then the market answers.

Sometimes it says:

“Yes.”

Sometimes:

“Not yet.”

And sometimes:

“No.”

The entrepreneur’s job is not simply to celebrate the «yes.»

It is also to listen carefully to the «no.»

Harvard Business School professor Amy Edmondson has emphasized that organizations need to distinguish between different kinds of failure. Some failures are preventable, while others emerge from complexity or from intelligent experimentation at the frontier of what is known. The goal isn’t to glorify failure; it is to understand what happened and learn appropriately from it.

That distinction is crucial.

Not every failure deserves applause.

Some failures happen because people ignored obvious warnings, failed to prepare, or repeated known mistakes.

Those should be prevented.

Other failures happen because a team made a reasonable experiment, accepted a calculated risk, and discovered something the market had not yet revealed.

Those can become valuable sources of knowledge.

The difference is learning.


🧠 The Science of a Growth Mindset

Why do some people recover from setbacks while others become discouraged by them?

Part of the answer lies in how we interpret our abilities.

Psychologist Carol Dweck’s work on growth mindset distinguishes between viewing abilities as relatively fixed and viewing them as capable of development.

A fixed mindset can interpret failure as evidence of inadequacy:

“I’m not talented enough.”

“I’m not good at business.”

“I’ll never be able to lead people.”

A growth-oriented mindset asks different questions:

“What can I improve?”

“What strategy should I try next?”

“What did this experience teach me?”

“What can I do differently?”

The word “yet” can be surprisingly powerful.

“I can’t do this…”

yet.

“I don’t know how to sell…”

yet.

“I don’t know how to lead a team…”

yet.

“I don’t understand financial statements…”

yet.

The point isn’t to pretend that effort automatically guarantees success. It doesn’t.

The point is to recognize that skills can be developed and that setbacks don’t necessarily define your future. Stanford’s research and teaching resources continue to describe growth mindset as a way of reframing perceived failures as opportunities for learning and development.


Don’t Turn Failure Into Your Identity

One of the most damaging things an entrepreneur can do is turn a business outcome into a personal judgment.

“My company failed” becomes:

“I’m a failure.”

“I made a bad decision” becomes:

“I make bad decisions.”

“I lost an important client” becomes:

“I’m terrible at sales.”

Notice what happened.

A specific event became a permanent identity.

But that’s not necessarily true.

You can make a poor decision and become a better decision-maker.

You can lose a customer and improve your sales process.

You can hire the wrong person and become better at evaluating talent.

You can launch the wrong product and become better at validating market demand.

Your results are information. They are not your identity.

That distinction gives you room to learn.

And learning requires honesty.


The Most Common Entrepreneurial Mistake

Confusing perseverance with stubbornness

You’ve probably heard:

“Never give up.”

It’s inspiring.

But it’s incomplete.

Because sometimes the smartest thing an entrepreneur can do is change direction.

Perseverance doesn’t mean doing the same thing forever.

It means remaining committed to the purpose while being willing to change the strategy.

You might need to change:

  • Your product.
  • Your pricing.
  • Your target market.
  • Your sales channel.
  • Your marketing message.
  • Your business model.
  • Your team.
  • Your assumptions.

The entrepreneur who refuses to change because “we’ve already invested too much” may be falling victim to the sunk-cost trap.

Past investment should not automatically determine future decisions.

Ask instead:

“Knowing what I know today, would I make this same decision again?”

That question can be uncomfortable.

But it can also be liberating.


The Lesson of Sara Blakely

Sara Blakely, founder of SPANX, has shared a story about how her father approached failure.

Instead of asking only what she had accomplished, he would ask:

“What did you fail at this week?”

The idea wasn’t to celebrate poor results.

It was to encourage experimentation.

If the answer was “nothing,” perhaps she hadn’t taken enough risks or tried enough new things.

That lesson became part of her entrepreneurial mindset.

And it highlights an important principle:

If you’re terrified of failure, you may eventually become terrified of trying.

Innovation requires experimentation.

Experimentation creates uncertainty.

And uncertainty means that some experiments won’t work.

The objective isn’t to fail recklessly.

The objective is to create an environment where reasonable experiments can produce useful learning.


Airbnb: When the Problem Wasn’t the Idea

Airbnb provides another useful lesson.

In its early days, the company struggled to generate enough traction.

The founders could have concluded:

“People don’t want this.”

Instead, they looked more closely at the customer experience.

One problem they identified was poor-quality photography.

Potential guests couldn’t properly understand what they were being offered.

The founders went directly to properties and improved the photographs.

That seemingly simple change helped improve the customer experience.

The larger lesson is powerful:

When something doesn’t work, don’t immediately reject the entire idea. Find out which assumption is failing.

Sometimes the problem is the product.

Sometimes it’s the price.

Sometimes it’s the message.

Sometimes it’s the distribution.

Sometimes it’s the customer.

And sometimes…

it’s the idea itself.

The point is to find out which one.


🧭 Persevere in Purpose. Adapt the Path.

One of the most valuable habits an entrepreneur can develop is the ability to distinguish between vision and strategy.

Your vision may remain stable.

Your strategy should not be sacred.

You may want to build a company that improves people’s financial lives.

The exact product you launch may change.

You may want to create an educational platform.

The technology may change.

You may want to build a sustainable agricultural business.

The market model may evolve.

This is what adaptation looks like.

Hold your purpose firmly. Hold your strategy lightly.

That’s not weakness.

That’s strategic maturity.


The Five-Question Post-Mortem

After a project, launch, campaign, or major decision doesn’t produce the expected result, resist the temptation to immediately look for someone to blame.

Instead, conduct a simple review.

Ask:

1. What did we expect to happen?

Be specific.

2. What actually happened?

Separate facts from assumptions.

3. What worked?

Don’t allow disappointment to erase what went well.

4. What didn’t work?

Be honest without becoming destructive.

5. What will we change next time?

This is the most important question.

Because reflection without action is simply analysis.

The purpose of a post-mortem isn’t to create a courtroom.

It’s to create a classroom.

Research on organizational learning shows that teams often struggle to learn from failure because blame discourages people from openly discussing mistakes. Effective learning requires leaders to create conditions where people can report problems, examine them, and experiment responsibly.


Build Your Failure Resume

Most resumes tell the world what went right.

Degrees.

Promotions.

Awards.

Successful projects.

Achievements.

But what if you created a second document?

Your Failure Resume.

List:

  • Projects that didn’t work.
  • Customers you lost.
  • Decisions you would make differently.
  • Investments that taught you difficult lessons.
  • Jobs you left.
  • Partnerships that didn’t work.
  • Skills you discovered you needed to develop.

Then add one column:

What did I learn?

For example:

ExperienceWhat I Learned
Lost an important clientI need a stronger follow-up system.
Poor product launchI need better market validation.
Wrong business partnerShared values matter as much as complementary skills.
Overspent on marketingI need clearer metrics before increasing the budget.
Hired too quicklyCultural fit and character deserve more attention.

Suddenly, the document doesn’t look like a list of failures.

It looks like a record of experience.


Five Ways to Recover Faster From Failure

1. Separate the result from your identity.

You failed at something. You are not a failure.


2. Write down three lessons.

Don’t close the chapter until you know what you learned.


3. Ask for feedback.

Sometimes other people can see what you couldn’t.


4. Change one important variable.

If you change everything at once, you may never know what actually improved the result.


5. Take another intelligent step.

Learning becomes powerful when it changes behavior.

Don’t simply understand the lesson.

Apply it.


🚀 The 7-Day Challenge

Turn One Failure Into a Teacher

For the next seven days, choose one experience that didn’t go the way you hoped.

You don’t have to publish it.

You don’t have to tell anyone.

This is for you.

Day 1. Write down exactly what happened.

Day 2. Separate facts from emotions.

Day 3. Identify three things you learned.

Day 4. Write what you would do differently today.

Day 5. Ask someone you trust for another perspective.

Day 6. Take one small action based on what you learned.

Day 7. Rewrite the story.

Instead of:

“I failed.”

Write:

“I tried something. It didn’t produce the result I wanted. I learned these lessons. And now I know what I will do differently.”

That’s not denial.

That’s growth.


The Kintsugi Lesson

There is a beautiful Japanese art form called kintsugi, in which broken pottery is repaired in a way that highlights rather than hides the cracks.

The repaired object carries evidence of its history.

Our professional lives can look the same.

Perhaps you’ve lost a business.

Maybe you’ve made a terrible investment.

Perhaps you’ve chosen the wrong partner.

Maybe you’ve lost a job.

Maybe you’ve launched something that nobody wanted.

Those experiences can become invisible wounds.

Or they can become visible evidence of what you’ve learned.

Your mistakes don’t have to disappear.

They can become part of your wisdom.

The goal isn’t to have a life without cracks.

The goal is to become wiser because of them.


Final Reflection

The entrepreneurial journey isn’t a straight line.

It’s a series of decisions.

Experiments.

Setbacks.

Discoveries.

Adjustments.

Small victories.

Unexpected problems.

And new beginnings.

The entrepreneur who never makes a mistake may simply be someone who never takes meaningful risks.

But there’s an important qualification:

Don’t romanticize failure.

Learn from it.

Prevent the mistakes that could have been prevented.

Experiment responsibly.

Take calculated risks.

Listen to customers.

Study the numbers.

Invite honest feedback.

And when something doesn’t work…

don’t waste the experience.

Use it.

Because the difference between a setback and a breakthrough is sometimes what you choose to do next.


💎 The Key Idea

“Failure doesn’t have to define you. It can educate you.”

Your company may fail.

Your strategy may fail.

Your investment may fail.

Your first attempt may fail.

But your story doesn’t have to end there.

You can accept.

You can learn.

You can adapt.

And you can move forward.

Accept → Learn → Adapt → Advance.

That is the cycle of the entrepreneurial mindset.
References

Dweck, C. S. (2006). Mindset: The new psychology of success. Random House.

Dweck, C. S. (2017). The journey to children’s mindsets—and beyond. Child Development Perspectives, 11(2), 86–91. https://doi.org/10.1111/cdep.12225

Edmondson, A. C. (2011). Strategies for learning from failure. Harvard Business Review, 89(4), 48–55.

Edmondson, A. C. (2023). The right kind of wrong: The science of failing well. Atria Books.

Seelig, T. (2015). Insight out: Get ideas out of your head and into the world. HarperOne.

Sinek, S. (2009). Start with why: How great leaders inspire everyone to take action. Portfolio.

Titulo de Video

Entrepreneur Mindset Ep 4 Failure Isn't the End

Entrepreneurial Mindset Ep 3 How to Make Decisions When Everything Feels Uncertain

This article is Episode 3 of our series:

Entrepreneurial Mindset

Great leaders don’t wait for certainty. They learn to move forward without it.

“Indecision is a decision too—and often, it is the most expensive one.”


The Cost of Waiting for the Perfect Decision

In 1994, Jeff Bezos had a successful career on Wall Street.

He had a good salary, professional stability, and a promising future.

By most standards, he had little reason to walk away.

But something caught his attention.

The Internet was growing at an extraordinary pace.

Bezos began to wonder what might happen if this new technology transformed the way people bought and sold products.

He saw an opportunity.

He also saw enormous risk.

If he left his secure career to start an Internet company, he could fail.

He could lose money.

He could damage his career.

And there was no guarantee that customers would ever buy anything online.

So he researched.

He analyzed the market.

He talked to people.

He considered the risks.

And eventually, he realized something important:

He would never have all the information he wanted.

Instead of asking himself, “What decision guarantees success?”, he asked a different question:

“When I’m 80 years old, will I regret trying—or regret not trying?”

That question helped him make the decision that eventually led to Amazon.

The lesson isn’t that Bezos knew exactly what would happen.

He didn’t.

The lesson is that he was willing to make an important decision without having absolute certainty.

And that is one of the most important skills an entrepreneur can develop.

Every business is built on decisions.

What product should we launch?

Who should we hire?

How much should we invest?

Which customers should we serve?

When should we change strategy?

When should we take a risk?

There is no formula that guarantees every decision will be right.

The goal is not to become someone who never makes mistakes.

The goal is to become someone who can make thoughtful decisions, learn quickly, and adjust when necessary.


We Often Wait for Guarantees That Will Never Come

One of the most common misconceptions in entrepreneurship is that successful people make decisions because they have more information than everyone else.

Sometimes they do.

But more often, they simply know when they have enough information to take the next step.

There is a major difference.

Waiting for complete certainty can become a sophisticated form of procrastination.

You tell yourself:

“I need more data.”

“I need to do more research.”

“I’ll decide when the market becomes clearer.”

“I’ll wait until the economy improves.”

“I need to be absolutely sure.”

Meanwhile, the market keeps moving.

Customers change.

Competitors innovate.

Technology evolves.

And opportunities disappear.

Entrepreneurship has never been about eliminating uncertainty.

It is about learning how to operate intelligently within it.

Think about companies such as Netflix, Airbnb, Apple, or Amazon.

None of them began with a guaranteed future.

They had ideas.

They had conviction.

They experimented.

They learned.

And they adjusted.

That’s the nature of entrepreneurship.


Why Is Decision-Making So Difficult?

Making an important decision means accepting responsibility.

And responsibility comes with the possibility of being wrong.

That possibility can trigger fear.

Fear of losing money.

Fear of failure.

Fear of criticism.

Fear of disappointing others.

Fear of damaging your reputation.

Sometimes, avoiding a decision feels safer than making one.

But there is a problem:

Not deciding is still a decision.

If you don’t launch the product, someone else might.

If you don’t contact the potential client, another company may.

If you don’t invest in your team’s development, your competitors may gain an advantage.

If you don’t adapt to a changing market, the market may eventually adapt without you.

Inaction can feel comfortable in the short term while becoming expensive in the long term.


The Science Behind Better Decisions

Our brains are designed to conserve energy and protect us from danger.

That is useful for survival, but it can create problems in modern business environments.

Every decision requires mental effort.

When we make too many decisions without sufficient recovery, we can experience what psychologists and researchers commonly refer to as decision fatigue.

Our ability to evaluate options carefully can decline.

This is one reason effective leaders create routines, systems, and priorities.

They don’t want to waste their best mental energy deciding what can be decided automatically.

Steve Jobs became famous for simplifying his wardrobe, for example, partly because reducing trivial choices allowed him to focus attention on more important matters.

The principle is simple:

Protect your mental energy for decisions that actually matter.


When Fear Distorts Our Decisions

Psychologist Daniel Kahneman’s research on judgment and decision-making demonstrated that human beings don’t always make purely rational choices.

We rely on mental shortcuts.

These shortcuts can be useful.

But they can also lead us astray.

One particularly important concept is loss aversion.

People often experience the pain of losing more intensely than the pleasure of gaining something of equivalent value.

For entrepreneurs, this can have serious consequences.

You may avoid launching a product because you are afraid of losing money.

You may refuse to hire an exceptional employee because the investment feels too large.

You may postpone entering a new market because you fear making a mistake.

You may continue using an outdated strategy simply because changing it feels risky.

The question is not whether fear will appear.

It will.

The question is:

Will fear make the decision for you?


The Mentor’s Lesson

Jeff Bezos and Type 1 vs. Type 2 Decisions

One of Jeff Bezos’ most useful leadership ideas is the distinction between Type 1 and Type 2 decisions.

Type 1 decisions

These are difficult—or sometimes impossible—to reverse.

Examples include:

  • Acquiring a company.
  • Selling a business.
  • Making a major long-term investment.
  • Entering a highly regulated market.
  • Making a decision that fundamentally changes the organization.

These decisions deserve careful analysis.

You need good information.

You need diverse perspectives.

And you should understand the consequences.

But then there are…

Type 2 decisions

These are generally reversible.

You can test them.

Adjust them.

Or abandon them.

Examples might include:

  • Testing a marketing campaign.
  • Launching a pilot program.
  • Changing a sales process.
  • Testing a new service.
  • Experimenting with a different pricing strategy.

One of the biggest mistakes organizations make is treating every decision as if it were irreversible.

They spend months analyzing decisions that could have been tested in a matter of days.

While they are analyzing…

The competition is learning.

And learning creates an advantage.


The 70% Principle

Bezos has also advocated making many decisions with roughly 70% of the information you wish you had, rather than waiting indefinitely for complete certainty.

This should not be interpreted as a rigid mathematical rule.

It is a mindset.
For high-stakes decisions involving safety, ethics, law, or enormous financial consequences, much more rigorous analysis may be appropriate.

But for many everyday business decisions, waiting for 100% certainty can mean waiting forever.

Ask yourself:

“Do I have enough information to take the next responsible step?”

If the answer is yes, you may already have enough to move forward.


Five Practical Tools for Better Decisions

1. Set a Decision Deadline

A decision without a deadline can remain unresolved indefinitely.

Give yourself a reasonable date.

Gather the information you need.

Consult the right people.

Then decide.


2. Separate Reversible from Irreversible Decisions

Ask:

“If this doesn’t work, can I change course?”

If the answer is yes, don’t treat the decision like a life-or-death choice.

Experiment.

Measure.

Learn.

Adjust.


3. Ask Better Questions

Instead of:

“What if I fail?”

Ask:

“What can I learn if this doesn’t work?”

Instead of:

“What if I make the wrong choice?”

Ask:

“Which option gives me the best opportunity to learn and move forward?”

Better questions create better thinking.


4. Seek Advice Without Surrendering Responsibility

Talk to mentors.

Listen to experts.

Ask your team.

Consider different perspectives.

But remember:

Advice can inform your decision. It cannot replace your responsibility for making it.

Leadership requires ownership.


5. Learn to Correct Quickly

A decision doesn’t have to be perfect to be valuable.

Sometimes the most valuable outcome of a decision is the information it produces.

You discover what customers want.

You learn what doesn’t work.

You identify an unexpected opportunity.

You find a weakness in your strategy.

The ability to correct course is one of the greatest competitive advantages an entrepreneur can develop.


Netflix Decided. Kodak Hesitated.

Business history gives us a powerful contrast.

Netflix began as a DVD rental company.

As Internet technology developed, the company recognized that digital distribution could fundamentally change entertainment.

The transition was risky.

Customers were not ready overnight.

The technology was still developing.

Yet Netflix continued moving toward streaming.

Kodak’s story is even more interesting.

The company actually developed one of the earliest digital camera prototypes.

The technology existed inside the organization.

But digital photography threatened the traditional film business that had made Kodak enormously successful.

The company struggled to fully embrace the transformation.

Meanwhile, competitors continued moving forward.

Eventually, the market changed so dramatically that Kodak could no longer rely on its historical position.

The lesson is not that every bold decision succeeds.

It is this:

Sometimes protecting today’s success can prevent tomorrow’s success.


Emotional Intelligence Matters

Good decision-making isn’t only about data.

It is also about emotional awareness.

Daniel Goleman’s work on emotional intelligence emphasizes the importance of recognizing and managing emotions.

Before making a major decision, ask yourself:

  • Am I responding to facts or fear?
  • Am I tired or emotionally overwhelmed?
  • Am I trying to protect my ego?
  • Am I avoiding this decision because it is genuinely risky—or because I am afraid of being wrong?
  • Am I considering the long-term consequences?

The goal isn’t to eliminate emotions.

That’s impossible.

The goal is to recognize them so they don’t quietly take control of the decision.


Your Seven-Day Decision Challenge

This week, choose one decision you’ve been postponing.

Write down:

Day 1

What exactly am I deciding?

Day 2

What information do I already have?

Day 3

What information do I genuinely need?

Day 4

What is the best realistic outcome?

Day 5

What is the worst realistic outcome—and how would I respond?

Day 6

Is this decision reversible?

Day 7

Make the decision.

Not necessarily the perfect decision.

The most responsible decision you can make with the information available today.

Then learn from what happens.


Reflection

A journalist once asked a mountaineer when he knew he would reach the summit.

The mountaineer reportedly answered:

“I never knew. I only knew the next step.”

That is also how entrepreneurship works.

You rarely see the entire mountain.

You see the next step.

And that next step is a decision.

You don’t need to know exactly how your business will look five years from now.

You need to know what you can do today to make that future more likely.

You don’t need perfect confidence.

You need enough courage to begin.

You don’t need to eliminate uncertainty.

You need to become capable of navigating it.

Because confidence doesn’t always come before action.

Very often, confidence is the result of action.

You make a decision.

You learn.

You adapt.

You make another decision.

And slowly, you discover that you are capable of handling far more uncertainty than you once believed.


Bibliografia aqui

Entrepreneurial Mindset Ep 3: How to make decisions when everything seems uncertain

7 Productivity Systems to Experiment With

Everyone—and their dog—has productivity advice to share. But let’s be honest: most of us struggle with productivity. We love to procrastinate, especially by reading articles about how to be more productive!

Working efficiently is about more than the color of your desk or the background music you play. It’s about finding a system that works for you and sticking with it. Over time, you’ll build positive habits that help you stay on track and get more done.

Fortunately, you don’t need to build a system from scratch. There are several proven frameworks that have worked for millions of people—you just need to find the right fit.

Since everyone works differently, there’s no one-size-fits-all solution. But if you’re willing to spend a little time experimenting, you can find a framework that will skyrocket your productivity in the long run.

Here are seven of the most popular productivity systems to test out:


1. Biological Prime Time

Developed by Sam Carpenter in his book Work the System, this method is all about listening to your body to discover when you are naturally most productive. If you’re someone who can stay laser-focused for hours and send emails without getting instantly distracted, this system might be for you.

  • How to do it: Spend a few weeks tracking your energy, focus, and motivation. Every hour or so, rate each on a scale from 1 to 10.

  • The takeaway: After a few weeks, you’ll have enough data to spot patterns (you can even graph them). Use these insights to schedule your most important and creative work during your peak hours.


2. Don’t Break the Chain

Rumored to have been created by comedian Jerry Seinfeld, this system came about when a young comic asked him for advice. Seinfeld told him that to become a better joke writer, he had to write every single day.

  • How to do it: Get a calendar (a paper one on your wall works best visually) and mark a big red X over every day you complete your task.

  • The takeaway: After a few days, you’ll create a chain. Your only goal is not to break the chain. Seeing that visual streak will keep you motivated to take action every day.


3. The Eisenhower Box

Used by U.S. President Dwight D. Eisenhower, this decision matrix helps you prioritize tasks and evaluate where to invest your time. If you constantly find yourself wasting hours on low-priority items, this system can help you regain control.

Categorize all your tasks into four quadrants:

  1. Urgent & Important: Do these immediately yourself.

  2. Important, but NOT Urgent: Schedule a specific time to do these later.

  3. Urgent, but NOT Important: Delegate these right away.

  4. Neither Urgent nor Important: Eliminate them completely.


4. Getting Things Done (GTD)

Created by David Allen, GTD is slightly more complex than other systems, but its main core principle is simple: your brain is for having ideas, not storing them.

  • How to do it: Write down every single task, commitment, and short-, medium-, or long-term goal in an external system (a notebook or an app). This clears up mental bandwidth for the task at hand.

  • The takeaway: Conduct a weekly review to organize and group similar tasks together (for example, batching all your phone calls into one session) and set your top priorities.


5. The Anti-To-Do List

Popularized by entrepreneur Marc Andreessen, this system is inspired by Arnold Schwarzenegger’s secret to success: keeping an open schedule to stay flexible for what matters most.

  • How to do it: Instead of writing down what you have to do, write down everything you’ve already accomplished throughout the day.

  • The takeaway: If you’ve ever reached the end of a long workday and wondered where all your time went, keeping an Anti-To-Do List helps you track, visualize, and celebrate your actual progress.


6. Must, Could, Want

Designed by entrepreneur Jay Shirley, this daily framework balances urgent priorities with long-term goals and personal well-being.

Every morning, answer these three questions:

  1. What MUST I do to create the biggest impact today? (Urgent/High priority)

  2. What COULD I do to build a better future? (Long-term goals)

  3. What do I WANT to do to enjoy today? (Personal satisfaction)

At the end of the day (or the next morning), review what you accomplished, reflect on any unfinished items, and adjust your focus accordingly.


7. The Pomodoro Technique

This classic technique breaks your workday into short, focused sprints separated by brief breaks, leveraging Parkinson’s Law (the idea that work expands to fill the time allotted for its completion).

  • How to do it: Pick a task and set a timer for 25 minutes (one Pomodoro). Work with 100% focus until the timer rings, then take a 5-minute break. After completing four Pomodoros, take a longer break of 15 to 30 minutes.

  • The takeaway: Time constraints create a sense of urgency that sharpens your focus, making it ideal for tasks like writing drafts, clearing out emails, or tackling heavy projects.


Final Thoughts

The real secret to productivity isn’t finding a trendy tool—it’s finding a system that fits your workflow and turning it into a habit. Feel free to experiment with these seven methods, tweak them, or combine them to build a routine that works best for you!

7 Ways to Organize Your Life: Choose the Ideal Productivity System for You

Entrepreneurial Mindset Ep 2 How to Stop Worrying About a Future That Hasn’t Happened Yet

This article is Episode 2 of our series:

Entrepreneurial Mindset

The Future Is Built by Today’s Actions, Not Tomorrow’s Worries


The Hidden Cost of Living in Tomorrow

It was just another Tuesday night.

Carlos, the owner of a growing technology company, had been sitting in front of his laptop for more than three hours. He wasn’t working anymore—he was worrying.

What if his biggest client left?

What if sales dropped next month?

What if the economy slowed down?

What if a stronger competitor entered the market?

What if he had made the wrong decision by starting his business?

As those questions echoed through his mind, the clock kept moving. It was almost two o’clock in the morning. His wife was asleep. His children were asleep. Yet he remained awake, fighting battles that hadn’t even begun.

The next morning, something remarkable happened.

None of the disasters he had imagined came true.

Still, he had already paid a heavy price: a restless night, mental exhaustion, and precious time he could have spent with the people he loved.

Does that sound familiar?

Many entrepreneurs spend their lives trapped between two places that don’t exist anymore—or don’t exist yet: yesterday and tomorrow. They replay past mistakes while fearing future uncertainty, forgetting that the only place where success can actually be built is the present moment.

Dale Carnegie captured this truth perfectly when he wrote:

«The best possible way to prepare for tomorrow is to concentrate with all your intelligence, enthusiasm, and determination on doing today’s work superbly today.»

Those words remain just as powerful today as they were decades ago.

Your future is not created by worrying about it.

It is created by what you choose to do today.


Why Does Our Brain Imagine the Worst?

Our brains were never designed to make us happy.

They were designed to keep us alive.

For thousands of years, survival depended on anticipating danger before it arrived. Those who noticed threats first were more likely to survive and pass on their genes.

That ancient survival system still operates today.

The difference is that most entrepreneurs aren’t running from predators anymore.

Instead, they imagine declining sales, losing investors, disappointing customers, making costly mistakes, or failing publicly.

Psychologists call this the negativity bias—our natural tendency to pay more attention to potential threats than to opportunities.

Ironically, the more ambitious we become, the easier it is to fall into this trap.

We try to predict every possible outcome.

Control every variable.

Prevent every mistake.

Yet the harder we chase certainty, the more anxious we often become.

The truth is simple:

Uncertainty is not the enemy of entrepreneurship.

It is the environment where entrepreneurship exists.

Every successful entrepreneur has learned to move forward without having all the answers.


The Science Behind Anticipatory Worry

Modern neuroscience helps explain why future worries feel so real.

When your brain perceives a possible threat, the amygdala—the brain’s emotional alarm system—activates a stress response even if the danger exists only in your imagination.

Stress hormones such as cortisol and adrenaline prepare your body to react.

That response is incredibly useful during genuine emergencies.

However, when your mind repeatedly creates imagined threats, your body remains in a constant state of alertness.

Over time, this can reduce creativity, impair decision-making, disrupt sleep, and weaken emotional resilience.

Research in psychology consistently suggests another surprising reality:

Most of the situations people spend time worrying about never actually happen.

Even when difficulties do arise, we usually cope far better than we expected.

In other words…

We often suffer twice.

Once in our imagination.

And once only if the problem actually appears.


The Mentor’s Lesson: Stephen Covey’s Circle of Influence

Stephen R. Covey introduced one of the most practical concepts in personal leadership: the distinction between the Circle of Concern and the Circle of Influence.

Your Circle of Concern includes everything that worries you:

The economy.

Competitors.

Political decisions.

Market trends.

Customer behavior.

Unexpected setbacks.

Your Circle of Influence includes something much more powerful:

Your preparation.

Your daily habits.

Your leadership.

Your character.

Your learning.

Your decisions.

Highly effective entrepreneurs spend far more energy inside their Circle of Influence than inside their Circle of Concern.

Not because they ignore reality.

But because they understand that progress comes from action—not anxiety.

Every minute spent improving yourself increases your ability to handle tomorrow.


Five Practical Ways to Stop Living in the Future

1. Shrink Your Time Horizon

Instead of asking, «What will happen next year?»

Ask,

«What is the most important thing I can accomplish today?»

Today’s actions shape tomorrow’s results.


2. Write Your Worries Down

Putting fears on paper creates emotional distance.

Many concerns lose their power the moment they become visible.


3. Replace Fear with Better Questions

Instead of asking,

«What if I fail?»

Ask,

«What can I learn regardless of the outcome?»

Great questions create great thinking.


4. Schedule Time to Reflect

Don’t allow worry to occupy your entire day.

Set aside a specific time to think strategically, then return your attention to meaningful work.


5. Celebrate Progress, Not Perfection

Confidence doesn’t come from having every answer.

It comes from repeatedly proving to yourself that you can move forward despite uncertainty.

Small victories build emotional resilience.


Final Reflection

Imagine meeting your future self five years from now.

How many of today’s worries would still matter?

Probably very few.

Not because life became easy.

But because you became stronger.

The future will always remain uncertain.

No entrepreneur can eliminate that reality.

Yet there is another truth that is just as powerful:

The future belongs to those who continue taking purposeful action while everyone else remains trapped in fear.

Don’t allow tomorrow’s imaginary problems to steal today’s opportunities.

Build.

Learn.

Adjust.

Keep moving.

One day you’ll realize that success didn’t arrive because uncertainty disappeared.

It arrived because you learned to move forward despite it.


«Worry may knock on your door, but you decide whether it becomes a guest—or a permanent resident. The future is prepared through action, never through anxiety.»

References

Carnegie, D. (1990). How to Stop Worrying and Start Living. Pocket Books. (Original work published 1948).

Covey, S. R. (2020). The 7 Habits of Highly Effective People. Simon & Schuster.

Dweck, C. S. (2016). Mindset: The New Psychology of Success. Ballantine Books.

Frankl, V. E. (2006). Man’s Search for Meaning. Beacon Press.

Kahneman, D. (2011). Thinking, Fast and Slow. Farrar, Straus and Giroux.

Seligman, M. E. P. (2011). Flourish. Free Press.

How to stop worrying about a future that doesn't exist yet

10 Mistakes That 99% of Entrepreneurs Make (and How You Can Avoid Them)

Every Great Business Begins with a Lesson

Every successful entrepreneur has one thing in common: they have made mistakes. Some mistakes cost time, others cost money, and a few can even threaten the survival of a business. Yet failure itself is rarely the real problem. The greatest danger is repeating the same mistakes because no one took the time to learn from those who came before.

The entrepreneurial journey is exciting because it offers the opportunity to transform ideas into reality, create jobs, solve meaningful problems, and leave a lasting impact on society. However, enthusiasm alone is not enough. Building a sustainable company requires discipline, humility, continuous learning, and the willingness to adapt.

Whether you are launching your first startup, managing a growing business, or simply interested in entrepreneurship, understanding the most common mistakes can help you make better decisions and accelerate your personal and professional growth.

Here are ten mistakes that countless entrepreneurs make—and practical ways to avoid them.


Learning Before Leading: Build the Right Foundation

1. Believing the Idea Is Everything

Many entrepreneurs believe their business idea is their greatest asset. In reality, ideas are abundant. Execution is what creates value.

History has shown that average ideas, executed exceptionally well, often outperform brilliant ideas that never move beyond the planning stage. Customers ultimately pay for solutions, not concepts.

Instead of asking, «Is my idea perfect?» ask, «Can I consistently deliver value?»

2. Trying to Build Everything Alone

Entrepreneurship is often portrayed as a lonely journey, but successful companies are rarely built by one person.

Every entrepreneur has strengths and weaknesses. A balanced team combines different perspectives, technical expertise, creativity, communication skills, financial knowledge, and operational discipline.

The smartest founders don’t try to be experts in everything—they surround themselves with people who complement their abilities.

3. Refusing to Recognize Personal Limitations

Confidence is essential, but overconfidence can become dangerous.

Self-awareness allows entrepreneurs to identify areas where they need advice, training, or experienced partners. The willingness to admit «I don’t know» is often the beginning of real growth.

Strong leaders never stop learning.


Great Products Need Great Business Strategies

4. Assuming Great Products Sell Themselves

One of the most expensive misconceptions in entrepreneurship is believing that quality alone guarantees success.

A remarkable product without marketing is like opening a beautiful store in the middle of a desert.

Customers must first discover your product, understand its value, trust your brand, and feel motivated to buy.

Marketing, communication, customer service, and relationship-building are not optional—they are essential components of every successful business.

5. Starting Without a Plan

Entrepreneurs often hear advice such as «Just start.»

Starting is important, but direction matters just as much.

A business plan does not need to predict every detail. Instead, it provides clarity about goals, customers, finances, competitive advantages, risks, and measurable milestones.

Plans may evolve, but operating without one usually leads to unnecessary confusion and wasted resources.

Remember: adjustment is part of entrepreneurship, but drifting without direction is not.

6. Raising Too Much—or Too Little—Capital

Money is fuel for business growth.

Too little funding can prevent a company from reaching profitability.

Too much funding can encourage unnecessary spending, oversized teams, expensive offices, or projects that do not generate value.

Healthy businesses learn to match available capital with realistic growth objectives.

Financial discipline is often more valuable than having unlimited resources.


Leadership, Resilience, and Sustainable Growth

7. Allowing Fixed Costs to Grow Too Quickly

Many entrepreneurs celebrate growth by increasing expenses before increasing revenue.

Large offices, excessive payroll, expensive subscriptions, and unnecessary infrastructure can quickly become financial burdens.

Whenever possible, businesses should remain flexible.

Variable costs generally provide more room to adapt than large fixed commitments, especially during uncertain economic periods.

Growth should strengthen financial stability—not weaken it.

8. Being Afraid of Failure

Failure has an unfair reputation.

Most successful entrepreneurs have experienced failed products, rejected proposals, disappointed customers, or unsuccessful investments.

Failure becomes valuable when it produces knowledge.

Every challenge teaches entrepreneurs something about markets, customers, leadership, or themselves.

The goal is not to avoid failure entirely—it is to fail intelligently, recover quickly, and improve continuously.

9. Confusing Being a Boss with Being a Leader

Authority comes from a title.

Leadership comes from trust.

A boss gives orders.

A leader develops people.

Employees are more committed when they feel respected, heard, and inspired by a shared purpose.

Great organizations are built by leaders who serve their teams, communicate clearly, recognize achievements, and create environments where people can perform at their best.

10. Settling Instead of Continuing to Improve

Success can become comfortable.

Comfort can become stagnation.

Markets evolve, technology advances, customer expectations change, and competitors continue improving.

The entrepreneurs who remain successful are those who never stop learning, questioning, experimenting, and innovating.

Continuous improvement is not a project with an end date—it is a mindset.

Personal Growth: The Greatest Competitive Advantage

Business success is rarely determined solely by intelligence or luck.

It depends on habits.

The discipline to keep learning.

The humility to seek advice.

The courage to make decisions despite uncertainty.

The patience to build long-term relationships.

The resilience to continue after setbacks.

Entrepreneurs who invest in their own personal development naturally improve their ability to lead others, solve complex problems, negotiate effectively, and recognize opportunities that others overlook.

In many ways, your business will only grow as much as you do.


Success, Happiness, and Purpose

Entrepreneurship is not simply about generating profits.

It is about creating value for customers, opportunities for employees, and positive contributions to society.

True success is achieved when professional accomplishment aligns with personal fulfillment.

Financial results certainly matter, but so do integrity, relationships, health, continuous learning, and the satisfaction of building something meaningful.

The best entrepreneurs understand that success is measured not only by the businesses they create but also by the people they become throughout the journey.


Conclusion

Every entrepreneur will make mistakes. That is inevitable.

What separates successful business owners from the rest is not perfection—it is their willingness to learn, adapt, and keep moving forward.

Ideas create possibilities.

Teams create companies.

Leadership creates culture.

Learning creates lasting success.

Every decision you make today becomes part of the foundation of tomorrow’s business.

Choose to build that foundation with humility, preparation, resilience, and purpose.

A Final Thought

Your entrepreneurial journey will never be defined by the number of times you fall, but by the number of times you choose to stand up with greater wisdom than before. Keep learning, keep improving, and keep believing that your greatest business achievement is still ahead of you.

References

Blank, S., & Dorf, B. (2020). The Startup Owner’s Manual. K&S Ranch.

Collins, J. (2001). Good to Great. HarperBusiness.

Drucker, P. F. (2007). Innovation and Entrepreneurship. HarperBusiness. (Original work published 1985)

Ries, E. (2011). The Lean Startup. Crown Business.

10 Mistakes 99% of Entrepreneurs Make

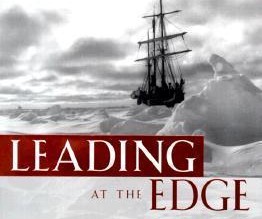
Leading at the Edge of Human Endurance

Inspired by Leadership Lessons of Ernest Shackleton by Dennis N. T. Perkins

Introduction

In 1914, the fearless explorer Ernest Shackleton set sail with a team of sailors and scientists on an ambitious mission: to complete the first land crossing of Antarctica. What followed became one of the most extraordinary survival stories ever recorded. Their ship, the Endurance, was crushed by the relentless pressure of Antarctic ice. Stranded in the frozen waters of the Weddell Sea, the crew faced months of unimaginable hardship, including dangerous open-boat voyages through the stormy Southern Ocean, freezing temperatures, starvation, isolation, and despair.

Yet throughout this harrowing ordeal, Shackleton demonstrated remarkable courage, creativity, resilience, and leadership. Day after day, he guided his men through seemingly impossible circumstances, ensuring that every member of the expedition survived. His leadership remains highly relevant today, especially in a business world characterized by fierce competition, rapid change, uncertainty, and constant demands for innovation. Organizations frequently find themselves operating at the edge of survival, making Shackleton’s lessons more valuable than ever.

Dennis N. T. Perkins’ book Leadership Lessons of Ernest Shackleton examines the expedition through a business lens, extracting ten powerful leadership strategies that can help modern leaders navigate crises, inspire teams, and achieve extraordinary results under pressure.


Strategy 1: Never Lose Sight of the Ultimate Goal—Focus on Short-Term Objectives

When the Endurance was destroyed, Shackleton’s dream of crossing Antarctica vanished instantly. Isolated from the world and with little hope of rescue, he quickly shifted his long-term objective. Instead of completing the expedition, his new mission became bringing every crew member home alive.

Leaders must recognize that changing conditions and unexpected challenges are inevitable. Successful leadership requires the flexibility to redefine goals when circumstances demand it, while maintaining the same commitment and energy dedicated to the original vision.

Business Example: Intel

During the mid-1980s, Intel was primarily known for manufacturing memory chips. However, aggressive competition from Japanese producers severely damaged the company’s profitability. Faced with mounting losses, Intel’s CEO, Andy Grove, made a bold decision: abandon the memory-chip business and focus entirely on microprocessors.

This strategic pivot transformed Intel into one of the world’s most successful technology companies.


Strategy 2: Lead by Example Through Visible and Memorable Actions

During times of uncertainty, visible leadership can determine whether a team succeeds or fails. Shackleton understood the importance of demonstrating commitment through actions rather than words alone.

When the crew had to abandon unnecessary possessions to continue their journey by sled, Shackleton dramatically discarded his own gold coins and a valuable gold cigarette case in front of the men. His message was unmistakable: survival mattered more than status or wealth.

Business Example: Continental Airlines

When Gordon Bethune became CEO of Continental Airlines, the company was crippled by bureaucracy and poor customer service. To symbolize a new culture, Bethune publicly burned the company’s cumbersome policy manual.

The gesture communicated a clear message: stop blindly following rules and start using judgment, creativity, and common sense to serve customers effectively.


Strategy 3: Inspire Optimism and Confidence While Remaining Grounded in Reality

Technical expertise and business acumen are essential leadership qualities. However, the ability to remain optimistic during adversity often distinguishes exceptional leaders from average ones.

Shackleton constantly encouraged his crew to imagine future opportunities, maintaining morale even in desperate circumstances. He understood that hope is not denial of reality—it is the determination to believe that a better future remains possible.

Effective leaders balance realism with optimism, acknowledging challenges while inspiring confidence in the team’s ability to overcome them.


Strategy 4: Take Care of Yourself—Maintain Your Endurance and Let Go of Guilt

Leaders who operate under extreme pressure often neglect their own well-being. Yet sustainable leadership requires physical and mental resilience.

Despite suffering from recurring health problems, Shackleton rarely complained. He recognized that maintaining his strength was essential not only for himself but for the survival of the entire team.

Business Example: Jürgen Schrempp

Former DaimlerChrysler CEO Jürgen Schrempp emphasized personal renewal through exercise, outdoor activities, and disciplined routines. His philosophy was simple:

«Work hard, take a cold shower, and the world looks different.»

Leaders cannot effectively care for others if they fail to care for themselves.


Strategy 5: Reinforce the Message of Unity—We Live or Die Together

Shackleton knew that survival depended on extraordinary teamwork. Individual success meant little if the group failed.

He consistently reinforced a sense of collective identity. Daily gatherings, shared activities, and open discussions strengthened social bonds and fostered mutual trust among the crew.

Business Example

One global financial institution recruited high-performing bankers with lucrative individual compensation packages. While financially attractive, these arrangements encouraged competition rather than collaboration.

As a result, departments operated in silos, and teamwork suffered. The lesson is clear: organizations thrive when employees identify with a common mission rather than solely pursuing personal rewards.


Strategy 6: Minimize Status Differences and Promote Respect

One hallmark of Shackleton’s leadership was his ability to eliminate unnecessary hierarchy. Scientists, doctors, sailors, and officers all shared responsibilities and worked side by side.

He also ensured fairness in the distribution of resources. When there were not enough high-quality sleeping bags for everyone, he refused special treatment and accepted the same conditions as many of his crew members.

Business Example

Organizations naturally require structure and authority. However, employees become disengaged when they perceive an elite class receiving privileges unavailable to everyone else.

Effective leaders create environments where every individual feels respected, valued, and essential to the mission.


Strategy 7: Master Conflict Management

Conflict is unavoidable whenever people work closely together under pressure. Shackleton viewed conflict management as one of his most important responsibilities.

When crew member John Vincent began behaving aggressively toward others, Shackleton acted decisively. He demoted Vincent and made it clear that such behavior would not be tolerated.

Leaders must address problems early before they escalate and damage team cohesion.

Business Application

Ignoring difficult personalities or isolating dissenters often creates larger problems. Instead, effective leaders engage them constructively, providing opportunities to contribute while preventing destructive power struggles.

As the Roman general Scipio advised, always leave opponents a «silver bridge» to retreat across rather than cornering them into desperate resistance.


Strategy 8: Find Reasons to Celebrate and Laugh

Even in the harshest conditions, Shackleton encouraged humor, celebrations, and social activities. Dog races, storytelling, jokes, and practical jokes became essential tools for maintaining morale.

Laughter helped relieve stress, strengthen relationships, and create emotional resilience.

Business Example: Southwest Airlines

Herb Kelleher, the legendary CEO of Southwest Airlines, famously used humor as a leadership tool. He frequently appeared at company events dressed as Elvis Presley or other colorful characters.

This culture of fun encouraged innovation, improved employee engagement, and contributed significantly to the company’s success.


Strategy 9: Be Willing to Take the Big Risk

After reaching Elephant Island, Shackleton knew waiting for rescue was not an option. Instead, he chose to undertake one of the greatest small-boat voyages in history: a 1,300-kilometer journey through some of the world’s most dangerous waters to reach South Georgia Island and organize a rescue mission.

The decision involved enormous risk, but inaction would almost certainly have led to disaster.

Business Example: Egghead.com

Facing severe financial losses, software retailer Egghead.com made the bold decision to close all physical stores and transition entirely to online operations.

While risky, the move reflected a leader’s willingness to confront reality and take decisive action when circumstances demanded it.


Strategy 10: Never Give Up—There Is Always Another Move

The story of the Imperial Trans-Antarctic Expedition is ultimately a story of perseverance. Time after time, the crew faced setbacks that could have ended their journey. Yet they refused to quit.

Shackleton also understood the importance of creativity. Interestingly, some of the expedition’s best ideas came from individuals who were often considered difficult or unconventional.

Business Example: Sun Microsystems

Scott McNealy, former CEO of Sun Microsystems, built a reputation for challenging conventional wisdom. Under his leadership, Sun pioneered networked computing, introduced Java, and developed innovative software technologies that reshaped the technology landscape.

Creative persistence requires flexibility. When one strategy fails, leaders must be willing to adapt, experiment, and continue searching for solutions.


Conclusion

Ernest Shackleton’s Antarctic expedition remains one of history’s greatest leadership case studies. His success was not measured by achieving the original mission, but by his ability to adapt, inspire, unite, and protect his people under the most extreme conditions imaginable.

Today’s leaders may not face Antarctic icebergs, but they do encounter economic uncertainty, technological disruption, organizational change, and intense competition. Shackleton’s ten leadership strategies offer timeless guidance for navigating these challenges.

The ultimate lesson is simple yet profound: great leadership is not about controlling circumstances. It is about inspiring people to move forward together when circumstances seem impossible.

As Shackleton demonstrated, true leaders do not merely survive adversity—they help others find the strength to overcome it.

Bibliografia aqui

Shackleton's Inspirational Leadership

WORLD BRAIN DAY Protecting Our Greatest Asset

Protecting Our Greatest Asset: Understanding Brain Health, Potential, and Well-Being

The Organ That Makes Us Who We Are

Imagine for a moment that you could insure the most valuable asset you possess. Many people would think of their home, their business, their savings, or their family’s financial future. Yet there is an asset that makes all of those things possible: the human brain.

Every thought, dream, memory, decision, and relationship begins within this remarkable organ. It helps us learn, create, solve problems, experience emotions, and connect with others. Despite its importance, many people devote more attention to maintaining their vehicles or electronic devices than to caring for their brain health.

As we recognize World Brain Day, we are reminded of the importance of understanding the incredible potential of the human brain, becoming aware of the risks that can affect it, and taking practical steps to protect one of the most important foundations of our quality of life. Just as we have previously discussed protecting our families through insurance, savings, and financial planning, it is equally important to protect the health that allows us to enjoy those resources and opportunities.

The Extraordinary Potential of the Human Brain

The human brain is one of the most complex structures known to science. Although it weighs only a few pounds, it contains billions of nerve cells that communicate through intricate networks, allowing us to think, learn, adapt, and innovate.

One of its most remarkable characteristics is its ability to change throughout life. This phenomenon, known as neuroplasticity, allows the brain to form new connections, learn new skills, and adapt to new circumstances. Whether someone is learning a language, developing professional expertise, or mastering a hobby, the brain continues to evolve.

This ability highlights an important lesson for personal and professional development: growth does not stop with age. Continuous learning, curiosity, and intellectual engagement help maintain cognitive function while opening doors to new opportunities.

For business leaders, entrepreneurs, and professionals, the brain is the engine behind creativity, strategic thinking, decision-making, and innovation. Investing in mental development is therefore not only a health decision but also a personal and professional investment.

Understanding Brain Risks and Common Neurological Diseases

While the brain possesses extraordinary capabilities, it can also be affected by various conditions that impact quality of life, independence, and overall well-being.

Some of the most common neurological conditions include Alzheimer’s disease and other forms of dementia, which affect memory and cognitive abilities. Parkinson’s disease impacts movement and coordination. Stroke can occur when blood flow to part of the brain is interrupted, potentially causing significant physical and cognitive challenges.

Epilepsy, migraines, traumatic brain injuries, and multiple sclerosis are additional conditions that affect millions of individuals worldwide. Mental health conditions such as depression and anxiety, while often discussed separately, are also closely connected to brain function and overall neurological health.

It is important to recognize that not every neurological condition can be prevented. However, awareness, early detection, medical attention, and healthy lifestyle choices can often improve outcomes and quality of life.

Rather than creating fear, understanding these risks empowers individuals and families to make informed decisions regarding prevention, healthcare, and long-term planning.

Brain Health, Disability, and the Importance of Inclusion

World Brain Day also encourages reflection on the experiences of individuals living with neurological conditions and disabilities.

A neurological disability does not define a person’s value, intelligence, or potential. Many individuals facing cognitive or physical challenges continue to make meaningful contributions to their families, workplaces, and communities.

Creating inclusive environments benefits everyone. Schools, businesses, healthcare systems, and communities that embrace accessibility and support allow individuals with neurological conditions to participate more fully in society.

Compassion, understanding, and education help reduce stigma and encourage earlier diagnosis and treatment. When society focuses on capabilities rather than limitations, opportunities for growth and participation expand significantly.

As leaders, employers, educators, and community members, we all have a role to play in promoting inclusion and supporting those affected by neurological conditions.

Personal Development, Success, and Happiness Through Brain Care

Success and happiness are often associated with external achievements, but both are deeply connected to brain health.

Healthy cognitive function supports emotional resilience, sound decision-making, productivity, creativity, and meaningful relationships. Taking care of the brain is therefore an investment in overall well-being.

Simple habits can make a meaningful difference. Regular physical activity supports blood flow to the brain. Quality sleep allows the brain to recover and process information. Balanced nutrition provides essential nutrients. Lifelong learning keeps the mind engaged. Social connections support emotional health, while stress management contributes to mental balance.

Just as financial planning involves making consistent choices over time, brain health is built through daily habits and intentional decisions. Small actions practiced consistently can contribute to long-term well-being.

Protecting brain health is not solely about avoiding illness; it is about maximizing potential, maintaining independence, and improving quality of life throughout the years.

Caring for the Mind That Shapes Our Future

World Brain Day offers an opportunity to appreciate the remarkable organ that influences every aspect of our lives. The brain enables us to learn, lead, innovate, love, and contribute to society.

By understanding neurological risks, promoting awareness, supporting inclusion, and adopting healthy habits, we take meaningful steps toward protecting one of our most valuable assets.

Just as financial security helps prepare us for life’s uncertainties, brain health preparation helps us preserve the abilities that allow us to pursue our goals, support our families, and enjoy life’s experiences.

Reflection

Your brain is the source of your ideas, your dreams, your resilience, and your capacity to create a better future. Every healthy choice, every new lesson learned, every meaningful conversation, and every effort to care for your well-being is an investment in your greatest asset. Protect it, challenge it, nurture it, and allow it to continue unlocking possibilities throughout your life.

References

Alzheimer’s Association. (2024). Alzheimer’s disease facts and figures.

World Federation of Neurology. (2024). World Brain Day resources.

World Health Organization. (2024). Neurological disorders: Public health challenges.

National Institute of Neurological Disorders and Stroke. (2024). Brain basics and neurological conditions.

Centers for Disease Control and Prevention. (2024). Healthy brain initiative.

World brain day

Understanding Financial Risk: Protecting Your Future While Building Your Dreams

Why Risk Matters More Than We Often Realize

Imagine spending years working hard, saving money, and making sacrifices to build a better future for yourself and your family. You finally decide to invest, hoping your money will grow and help you achieve important goals such as retirement, education, a home, or financial independence. Then, unexpectedly, markets fluctuate, inflation rises, currencies lose value, or an investment performs below expectations.

Experiences like these remind us that investing is not only about seeking returns; it is also about understanding and managing risk. Financial risk is a natural part of every investment decision. The good news is that risk does not have to be feared. When understood properly, it becomes a tool that helps us make better decisions and build a stronger financial future.

In a previous discussion, we explored the financial and securities system and how it connects investors with opportunities. Now, it is time to focus on one of the most important elements of investing: financial risk and how to align investment decisions with your personal goals, values, and tolerance for uncertainty.

Understanding Market and Credit Risk

Financial risk comes in many forms, but two of the most common are market risk and credit risk.

Market risk refers to the possibility that the value of an investment may fluctuate due to changes in economic conditions, interest rates, inflation, political events, consumer confidence, or global developments. Stocks, bonds, investment funds, and even real estate can be affected by market movements.

For example, an investor may purchase shares of a company expecting growth. However, economic uncertainty or changes in industry conditions may temporarily reduce the value of those shares. This does not necessarily mean the investment was a mistake; rather, it reflects the reality that markets move over time.

Credit risk, on the other hand, relates to the possibility that a borrower may fail to meet their financial obligations. When investing in bonds, debt instruments, or lending arrangements, investors rely on the ability of governments, companies, or individuals to repay what they owe. The lower the borrower’s ability to pay, the greater the credit risk.

Understanding these risks helps investors avoid making decisions based solely on emotions or short-term market events.

The Hidden Factors That Influence Investment Success

Many people focus exclusively on potential returns, but successful investing requires considering several interconnected factors.

Purchasing Power and Inflation

One of the greatest long-term financial risks is not always losing money—it can be losing purchasing power.

Inflation gradually increases the cost of goods and services. If your investments grow at a rate lower than inflation, your money may buy less in the future even if your account balance appears larger.

For this reason, investors should evaluate whether their investments have the potential to preserve or increase real purchasing power over time.

Profitability and Risk

There is a fundamental relationship between risk and return. Generally, investments that offer higher potential returns also involve higher levels of uncertainty.

This does not mean investors should always seek the highest returns available. Instead, they should seek an appropriate balance between potential growth and their ability to tolerate fluctuations.

The most suitable investment is not necessarily the one with the highest expected return, but the one that aligns with an individual’s goals and comfort level.

Profitability and Liquidity

Liquidity refers to how quickly an investment can be converted into cash without significantly affecting its value.

Some investments may offer attractive returns but require investors to commit funds for extended periods. Others provide easier access to money but may generate lower returns.

Finding the right balance between profitability and liquidity is essential, particularly when planning for emergencies, short-term objectives, or unexpected opportunities.

Devaluation and Currency Risk

In a global economy, currency movements can affect the value of investments and savings.

When a currency loses value relative to others, imported goods become more expensive, and purchasing power may decline. Investors should understand how currency fluctuations may influence their financial plans, especially when investing internationally or holding assets linked to foreign markets.

Opportunity Cost

Every financial decision involves a trade-off.

Opportunity cost represents the benefits that could have been gained from choosing an alternative option. For example, keeping all savings in a low-yield account may feel safe, but it may also limit long-term growth opportunities.

Evaluating opportunity costs helps investors think strategically rather than reactively.

Knowing Yourself: The Key to Risk Tolerance

Perhaps the most overlooked aspect of investing is self-awareness.

Risk tolerance refers to an individual’s ability and willingness to accept fluctuations in investment value. Some people remain calm during market volatility, while others experience significant stress when investments decline.

Neither approach is right or wrong. The important thing is to understand your personal comfort level and invest accordingly.

Factors that influence risk tolerance include:

  • Age and investment horizon.
  • Financial responsibilities.
  • Income stability.
  • Personal goals.
  • Previous investment experience.
  • Emotional response to uncertainty.

Investing beyond your comfort zone can lead to emotional decisions that undermine long-term success. Conversely, avoiding all risk may prevent your money from growing enough to meet future needs.

A thoughtful investment strategy recognizes both financial realities and human emotions.

Personal Growth, Financial Success, and Lasting Well-Being

Financial education is ultimately a form of personal development.

Learning about risk helps individuals become more confident, disciplined, and intentional in their decision-making. It encourages patience, long-term thinking, and a greater understanding of how daily choices influence future outcomes.

True financial success is not measured solely by wealth accumulation. It also includes peace of mind, freedom to pursue meaningful goals, and the ability to support the people and causes that matter most.

The most successful investors are often not those who predict markets perfectly, but those who remain committed to a well-designed plan, continue learning, and adapt responsibly to changing circumstances.

Conclusion

Financial risk is not an obstacle to success—it is a reality that accompanies every meaningful opportunity. By understanding market risk, credit risk, inflation, purchasing power, liquidity, devaluation, diversification, and opportunity cost, individuals can make more informed decisions and build greater confidence in their financial journey.

The future will always contain uncertainty, but knowledge transforms uncertainty into preparation. Every step taken to improve financial understanding is an investment in yourself, your family, and your dreams. The goal is not to eliminate risk entirely, but to manage it wisely so that your money works alongside your aspirations and supports a life of purpose, growth, and fulfillment.

References

Bodie, Z., Kane, A., & Marcus, A. J. (2024). Investments (13th ed.). McGraw-Hill Education.

Madura, J. (2023). Financial markets and institutions (14th ed.). Cengage Learning.

Mishkin, F. S., & Eakins, S. G. (2024). Financial markets and institutions (10th ed.). Pearson.

Reilly, F. K., & Brown, K. C. (2021). Investment analysis and portfolio management (11th ed.). Cengage Learning.

Ross, S. A., Westerfield, R. W., Jordan, B. D., Lim, J., & Tan, R. (2022). Fundamentals of corporate finance (5th ed.). McGraw-Hill Education.

Financial Education: The Art of Smart Decisions

Father’s Day: The Quiet Strength That Builds Secure Children

«What if the greatest gift a father gives is not what he buys… but the security he creates through his presence?»

Every year, Father’s Day reminds us to celebrate fathers, but its real meaning goes far beyond cards and gifts. Fatherhood is one of the most powerful influences on a child’s emotional growth, confidence, and future resilience.

Modern fatherhood is changing in remarkable ways.

In the United States, 93.7% of fathers with children under 18 participate in the workforce, showing the ongoing commitment fathers make to providing for their families. Additionally, 66.3% of married-couple households with children have both parents employed, reflecting the growing teamwork in parenting today.

But fatherhood is no longer defined only by financial provision.

Research consistently shows that involved fathers contribute to better emotional regulation, stronger academic outcomes, and greater autonomy in children. Children with engaged fathers are more likely to develop confidence, resilience, and healthier relationships later in life.

Why?

Because fathers often teach through action.

They model problem-solving.
They demonstrate persistence.
They show children what responsibility looks like in real life.

A father who calmly handles setbacks teaches emotional regulation.
A father who plans financially teaches long-term thinking.
A father who shows up consistently teaches security.

And in today’s world, that kind of consistency matters more than ever.

Financial planning is also a form of love.

Many people think life insurance is only about death. It isn’t.

It is about preserving stability for the people who depend on you. It protects education plans, family housing, daily expenses, and emotional peace during difficult moments.

Savings matter too.

When fathers create emergency funds, retirement plans, or educational investments, they’re not simply managing money—they’re building autonomy for future generations.

Children raised in financially stable homes often develop healthier relationships with money, lower anxiety around uncertainty, and greater resilience as adults.

But fatherhood isn’t about perfection.

No father gets everything right.

The most powerful fathers are not flawless; they are present.

They apologize when needed.
They learn.
They grow.

And through that process, they teach something invaluable: resilience is not never failing—it is rising again with love and purpose.

This is what makes secure children.

Not wealth alone.
Not status.
Not perfect parenting.

But consistency, emotional presence, and thoughtful preparation.

On this Father’s Day, celebrate the fathers who quietly create stability every single day.

The dads who wake up early.
The dads who listen.
The dads who plan for tomorrow while still showing up today.

Because real fatherhood is not measured by what a man owns.

It is measured by the security he creates in the hearts of those he loves.

The strongest legacy a father leaves is not money, but resilience, emotional regulation, and secure children who know they were deeply loved.

References

History and reality of Father's Day

International Anti-Bullying Day: Breaking the Silence and Building Safer Schools

Every child deserves to walk into school feeling safe, respected, and free to learn without fear. Yet millions of students around the world experience a different reality: repeated teasing, exclusion, humiliation, threats, or physical and online aggression. That is bullying, and its effects can follow a person for years.

That is why International Anti-Bullying Day is far more than a symbolic date. It is a global call for awareness, empathy, and action. It reminds us that behind every case is a child who needs support, a worried family, and a community that shares responsibility.

Modern society often speaks about innovation, growth, and progress. But no progress is complete if children grow up in fear. Protecting their emotional well-being is also building the future.


Bullying: A Social Problem That Affects Everyone

For many years, bullying was dismissed as “just kids being kids.” Today, we know better.

Bullying can lead to:

  • Anxiety and depression
  • Poor academic performance
  • School avoidance
  • Low self-esteem
  • Social isolation
  • Trust issues
  • Future aggressive behavior
  • Higher dropout risk

This does not only harm the victim. It affects classmates, teachers, families, and society as a whole.

When a child loses confidence, the world loses potential. When cruelty becomes normal, communities grow weaker.

International Anti-Bullying Day reminds us that early action can change lives.


The Future of Education Requires Empathy

We now live in a digital world where bullying does not always end after school. It can continue through social media, group chats, and online gaming.

That is why modern education must teach not only academic subjects, but also human skills such as:

  • Emotional intelligence
  • Peaceful conflict resolution
  • Respectful communication
  • Healthy digital behavior
  • Inclusion
  • Empathy

The future workplace will need leaders who can collaborate, listen, and solve problems. Those skills begin in childhood.

A child who learns respect today becomes a stronger adult tomorrow.


What Each of Us Can Do

Change does not belong only to institutions. It belongs to all of us.

Parents

  • Listen without judgment
  • Notice behavior changes
  • Teach respect at home
  • Seek help when needed

Teachers

  • Identify warning signs early
  • Intervene fairly and firmly
  • Build inclusive classrooms

Students

  • Do not laugh at cruelty
  • Include those who feel alone
  • Report serious situations
  • Defend kindness

Society

  • Speak openly about bullying
  • Support school campaigns
  • Promote youth mental health

Every action matters.


The Power of Example

Children learn more from what they see than from what they hear.

If they watch adults insult, shame, or discriminate, they may repeat those behaviors.

If they watch adults:

  • Speak calmly
  • Correct respectfully
  • Listen with empathy
  • Solve conflict peacefully

they learn that true strength is emotional maturity.


Conclusion

International Anti-Bullying Day should not remain a one-day campaign. It should become a daily commitment.

Every classroom can be a place of growth. Every family can be a safe space. Every community can be part of the solution.

Never underestimate the power of one kind word, one timely intervention, or one honest conversation.

Closing

Let us build a generation that uses its voice to defend, not to harm. A generation that sees differences as strength, not targets. A generation that understands kindness is also courage. Change begins today—with us. Because when we protect one child, we protect the future of all.

Bibliography 

Espelage, D. L., & Swearer, S. M. (2011). Bullying in North American schools (2nd ed.). Routledge.
Olweus, D. (1993). Bullying at school: What we know and what we can do. Blackwell Publishing.
UNESCO. (2019). Behind the numbers: Ending school violence and bullying. UNESCO Publishing.
World Health Organization. (2020). School violence and youth mental health. WHO.
Bandura, A. (1977). Social learning theory. Prentice Hall

International Anti-Bullying Day